Mortgage Guide
Paying Rent on Time but Thin Credit? How Renters Build History
Picture this. You've paid rent on your St. Pete apartment on time for four years, you have savings, and your job is steady. Then you check your credit and there's barely anything there. That's common. Rent often doesn't show up on credit reports, and thin history is now a top reason purchase loans get denied, but you can start fixing it this month.
How big is the credit history problem?
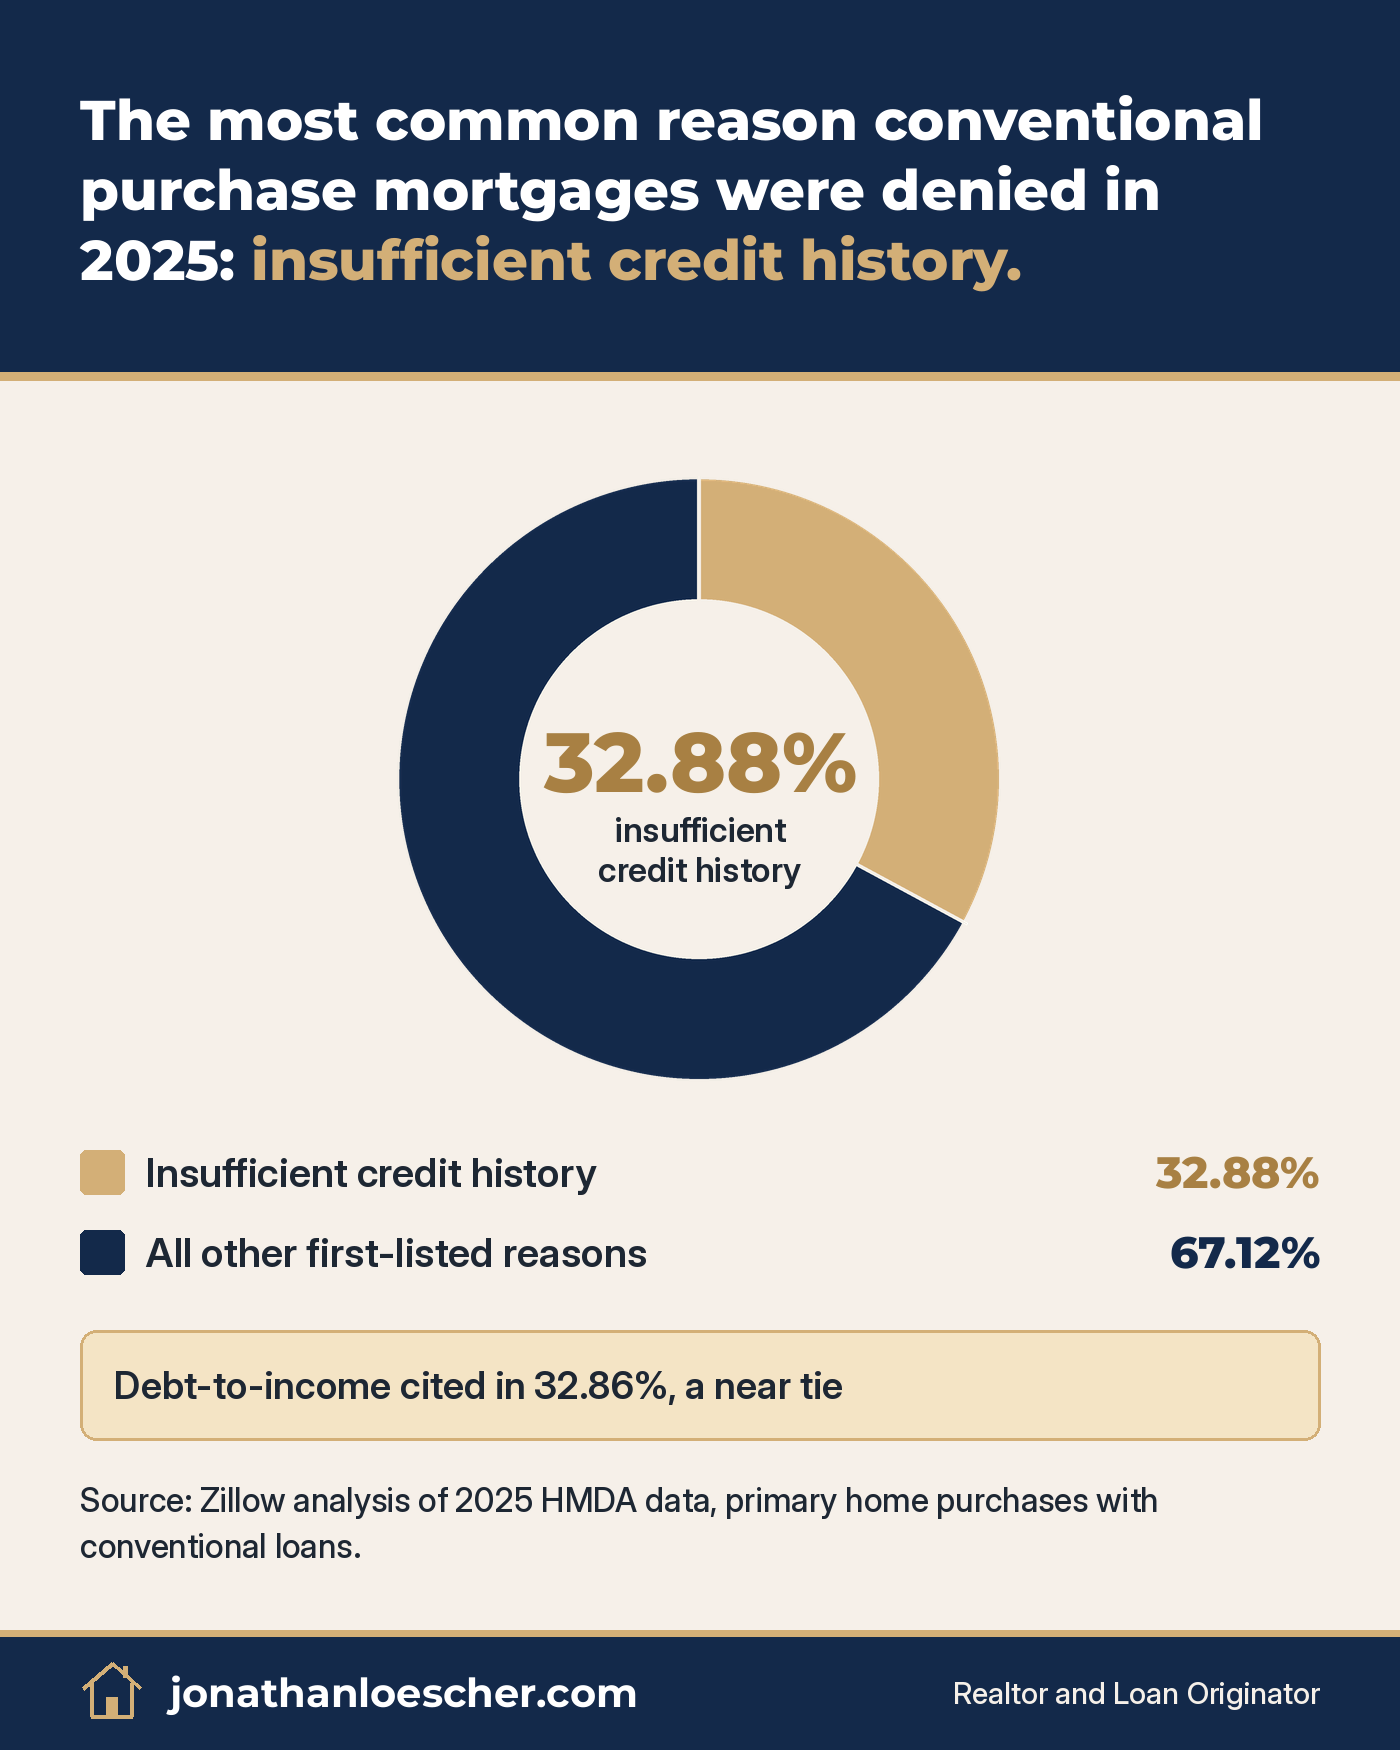
Zillow reviewed 2025 federal mortgage data collected under the Home Mortgage Disclosure Act. For conventional loans on primary home purchases, credit history was cited in 32.88% of denials. That edged out debt-to-income, cited in 32.86%.
So it's nearly a tie with having too much debt. The difference is that thin credit often has nothing to do with how responsible you are. It just means the system hasn't seen you pay much.
Why doesn't my rent count already?
Landlords aren't required to report rent to the credit bureaus, and many don't, as FICO explains. When rent does show up, it's often the bad kind, like an unpaid balance sent to collections.
VantageScore estimates that only about 13% of renters currently benefit from positive rent reporting. That leaves a lot of on-time payments invisible.
What's changing with credit scores?
For years, loans sold to Fannie Mae and Freddie Mac used one score model, Classic FICO. According to FHFA, lenders can now choose between Classic FICO and VantageScore 4.0 for those loans. As of September 9, 2026, VantageScore 4.0 is open to all approved lenders. FHFA notes the newer models can take rent payment history into account.
VantageScore studied more than 600,000 renters using data from Esusu. It found that nearly four million U.S. renters could reach a VantageScore 4.0 of 620 or higher if their on-time rent were reported. That's a research estimate, and it doesn't mean any one person will qualify.
Does every lender use the new model?
No, and that's the catch. Each lender picks which approved model to use on a given loan, and all borrowers on that loan get the same model. Classic FICO, the model many lenders still use, generally doesn't count rent data. FICO says its newer versions, FICO Score 9 and later, do include reported rent, but FHFA says FICO 10T isn't eligible yet for loans sold to Fannie and Freddie.
Government loans like FHA have their own rules, and some programs allow nontraditional credit, like rent and utility records. That's something we confirm at consult. If FHA is on your list, my FHA guide covers the basics.
How do I get my rent reported?
Start with your landlord or property manager. Ask if they report rent, and to which bureaus. Some complexes offer it as an opt-in you have to turn on.
If they don't, you can use a third-party rent reporting service. FICO lists several. Some are free, some charge a setup fee plus a monthly fee, and they don't all report to all three bureaus. Experian Boost is free and can add eligible rent, utilities, and phone payments to your Experian file. Before you pay for anything, check which bureaus it reaches and whether it can add past months.
What else builds history?
- Open a secured credit card, use it for one small bill, and pay it in full.
- Ask a family member with good habits to add you as an authorized user.
- Keep card balances low compared to your limits.
- Leave old accounts open, even if you rarely use them.
- Space out new applications instead of opening several at once.
None of this works overnight. History is about time, so the earlier you start, the more months you'll have on file when you apply.
What does a realistic plan look like?
Here's how I'd sketch it for a renter in Brandon or Largo with a thin file. In the first month, pull your reports, fix any errors, and ask your landlord about reporting. If they can't, pick a service that reaches the bureaus you need and see if it can add past months. Around the same time, open one secured card or join a family member's account as an authorized user.
Then let time do its part. Pay everything on time, keep balances low, and don't open anything new you don't need. Check back with me every few months so we can see what's showing up and adjust before you apply.
What if my report has mistakes?
Pull your reports from all three bureaus and read them line by line. Wrong addresses, accounts that aren't yours, and late marks you didn't earn all hurt. The CFPB lays out how to dispute an error, with the bureau and with the company that reported it. Keep copies of everything you send.
When should I talk to someone?
Sooner than you think. A thin file is one of the more fixable problems a renter can have, from Pinellas Park to Riverview. I'm Jonathan Loescher, a Realtor and Loan Originator in Tampa Bay, Florida, and I can look at your file and tell you what's missing, so you're not guessing.
I originate loans in Florida through PMF, Inc. (NMLS 1980), and the real estate file runs through Realty of America. You don't have to use both. Approvals stay conditional on lender review.
If you're ready to see where you stand, you can apply for a loan. If you're curious what your future budget could buy, browse Tampa Bay homes for ideas and plan for Florida closing costs too.
Your next step: book a consultation. We'll look at your credit together and map out what to build over the next few months.
Common questions
- Where is Bayou Club in Seminole, Florida?
- Bayou Club Estates is a gated golf community on the Seminole and Largo edge of Pinellas County. Most listings use a Seminole city and ZIP 33777. The gate is off Belcher Road. It is not in Seminole County. Open the Bayou Club homes for sale search for live listings.
- Where is Oakhurst Shores in Seminole, Florida?
- Oakhurst Shores is a west Seminole neighborhood in Pinellas County near Oakhurst Drive, Grove Street, and Boca Ciega Bay. Most sale files use ZIP 33772. It is not in Seminole County. Many homes may have water frontage, however being in this community does not guarantee water frontage. Search live files on the Oakhurst Shores homes for sale page.
- Where is Yacht Club Estates in Seminole, Florida?
- Yacht Club Estates is a Seminole neighborhood in Pinellas County. Listings cluster on streets such as Portside Drive and Commodore Drive in ZIP 33776. It is not Seminole County. The yacht-club name does not guarantee a slip or dock. Search live files on the Yacht Club Estates homes for sale page.
- Should I buy first or sell first in Tampa Bay?
- It depends on the loan, the equity, and the timing. I can model buy-before-you-sell as a lender program fee, not a brokerage commission, then list the current home. Book a call and we will run the numbers on your file.
- What does it cost to sell a home in Tampa Bay?
- Typical costs include payoff of the mortgage, negotiated brokerage compensation, title, prorated taxes, HOA or CDD transfer items, and any credits. Ask for a net sheet. Online estimates are not appraisals.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.
Have a question about how this applies to your home or loan?
Book a Call