Selling
Worried Your Buyer Will Back Out? How Tampa Bay Sellers Prepare
You accept an offer, and for a minute you can finally breathe. Then a friend tells you their buyer walked away two weeks before closing. Now you're wondering if that will happen to you.
It might. But it probably won't, and you have more control over it than you think. Here's what I see behind canceled deals in Pinellas and Hillsborough, and what I do with sellers to keep a contract together.
How often do home sales fall through?
Redfin tracks how many pending sales fall out of contract each month. In its October 12, 2026 report, Redfin said 14.5% of U.S. deals that went under contract in September were canceled. That's the highest share in its records outside the spring of 2020. Redfin listed the Tampa metro at 18.8% for the same month.
Cotality measures it a different way. In its September 24, 2026 release, it said nearly 12% of June contracts still hadn't closed after 60 days.
The honest answer is that most deals still close. By Redfin's September 2026 count, roughly one in seven doesn't, and the Tampa metro ran higher than the country. That's a reason to prepare. It isn't a reason to stay put.
Why are more buyers walking away?
Buyers have more homes to choose from, and in my experience, monthly costs have been stretching their budgets. When a buyer has options, a problem that once got negotiated now gets them to walk.
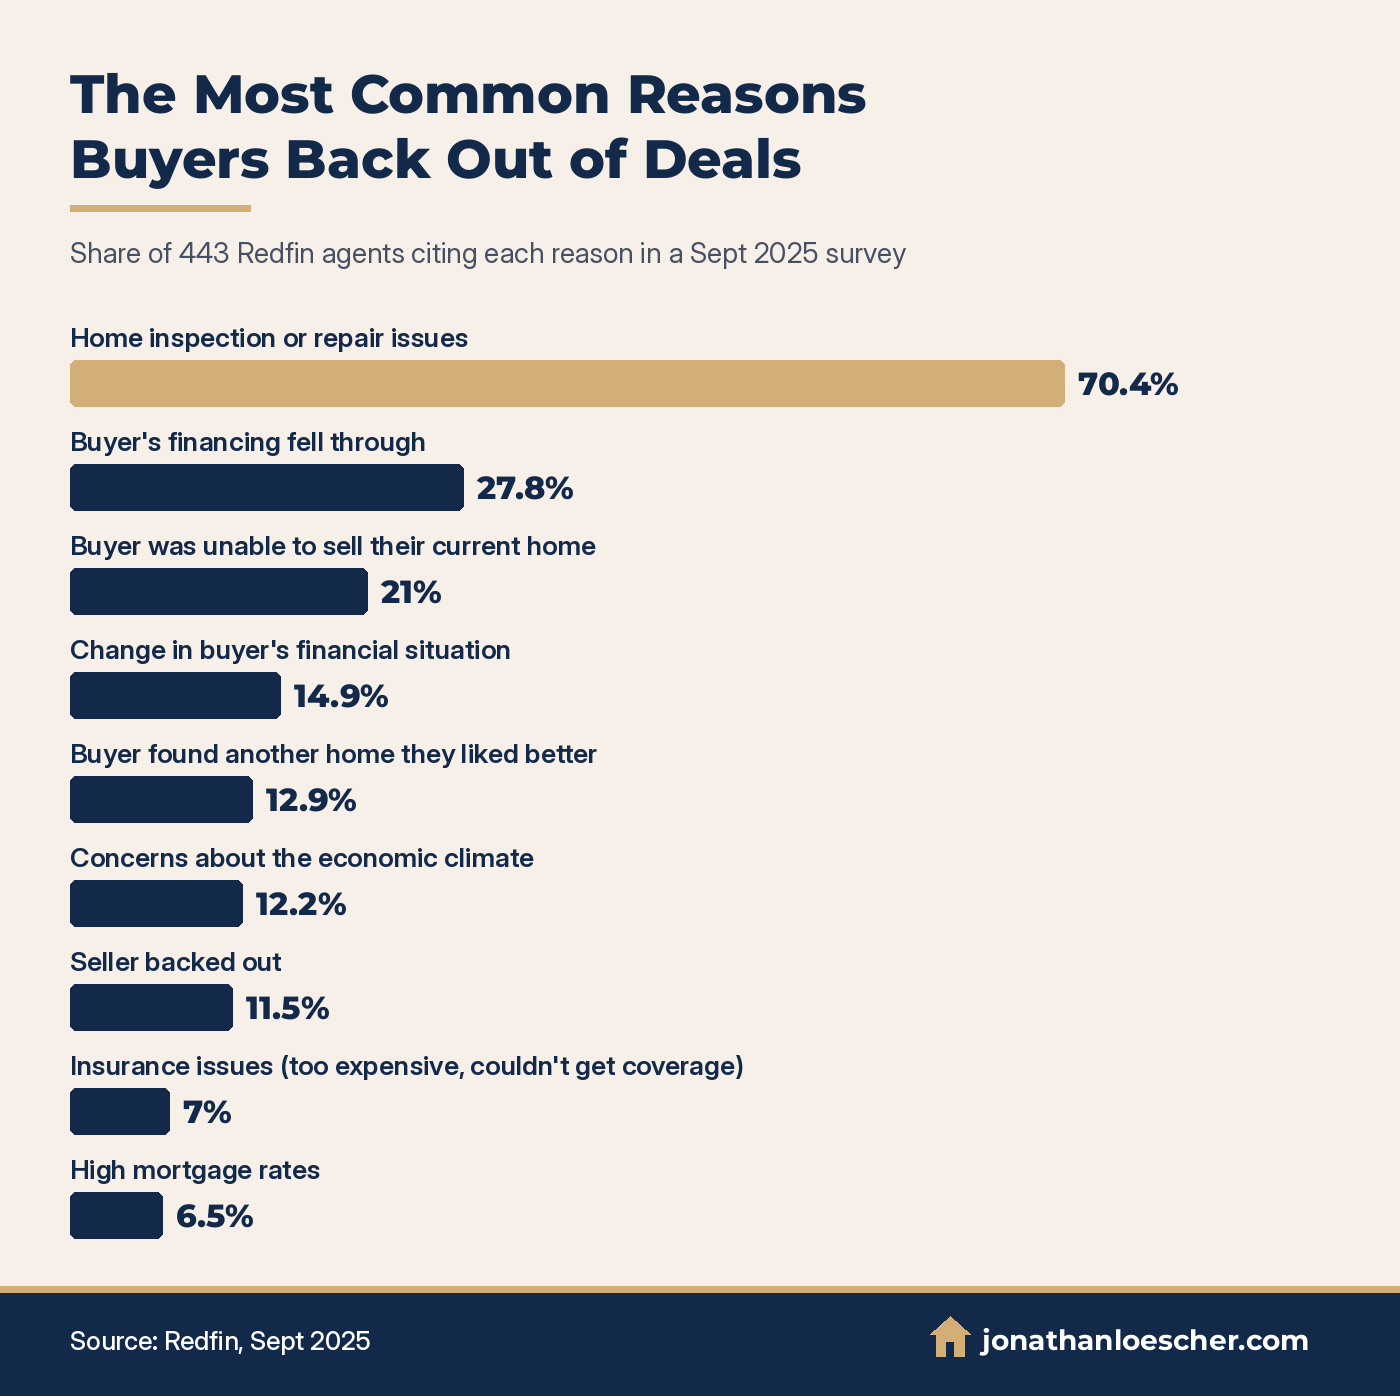
Redfin asked 443 of its agents who had handled a cancellation why their deals fell apart. That survey ran in September 2025. Inspection or repair issues topped the list at 70.4%. Buyer financing falling through came next at 27.8%, and a buyer who couldn't sell their current home followed at 21%.
Why Florida deals fall apart
National surveys don't capture how much insurance drives deals here. In my experience, these are the four spots where Tampa Bay contracts get shaky.
- The insurance quote. A buyer gets under contract, then the quote comes back far higher than they planned. My take: this hits the monthly payment hard enough that some buyers can no longer qualify, or no longer want to.
- The 4-point inspection. Insurers often ask for one on older homes. It looks at the roof, electrical, plumbing, and heating and cooling. An old panel or aging water heater can stop a policy from being written.
- Roof age. In my experience, an older roof can limit which carriers will quote the home at all, and it's the single item I see change buyers' minds most often in Pinellas.
- The appraisal. If the appraisal comes in below the price, the buyer's loan amount shrinks. Someone has to cover the gap, or the deal ends.
Wind mitigation matters too. In my experience, a good wind mitigation report can lower the buyer's premium. If you have one ready, a scary quote can become a workable one.
How can a seller reduce the risk?
You can't control a buyer's job or their nerves. You can control what they find and when they find it.
- Get a pre-listing inspection. Find the problems before a buyer does. Then you choose to fix them, price for them, or disclose them up front.
- Order a 4-point and wind mitigation report. If your home is older, this tells you early whether insurance will be a hurdle. Buyers can hand the reports to their insurance agent on day one.
- Know your roof. Have the install date, permit, and any repair records ready. If the roof is near the end of its life, we talk about it before we set the price.
- Gather your documents. Permits, receipts for major work, HOA or condo documents, and any assessment notices. Missing paperwork slows a deal, and slow deals die.
- Share insurance info early. If you know your current premium and carrier, share it with buyers. A real number beats the buyer's worst guess.
- Look hard at the offer, not just the price. I check the buyer's approval, the down payment, and whether they need to sell a home first. A slightly lower offer with a solid buyer can be the better deal.
How should you handle repair requests?
Repair requests are normal. They aren't a sign the buyer is leaving. Here's how I approach them with sellers.
- Sort the list. Separate safety and insurance items from cosmetic ones. Insurance items usually have to be dealt with for the buyer to close.
- Consider a credit instead of repairs. A credit lets the buyer handle the work their way, and it keeps your closing date on track.
- Answer fast. Inspection periods are short. A quick, clear reply keeps the buyer from cooling off.
- Know your walk-away line. Decide ahead of time what you will and won't do. It makes the conversation calmer.
If a deal does fall through, your home goes back on the market with better information. You'll know what scared the last buyer, and you can address it before the next one.
Mortgage tip: seller-paid buydowns and closing credits
When a buyer's budget is stretched, a seller concession can save a deal that the price alone can't. There are two common tools.
- Closing cost credits. You pay part of the buyer's closing costs. That lowers the cash they need to bring to closing.
- Seller-paid rate buydowns. You fund a lower interest rate for the buyer. Some buydowns last for the life of the loan, and others step up over the first few years.
Every loan program sets its own limit on how much a seller can contribute, and the right choice depends on the buyer's loan. Ask me for current terms before you offer one, or have your buyer start an application so we can see what fits.
Two companies, your choice
As a Realtor with Realty of America, I help you prepare and sell the home. As a Mortgage Loan Originator with PMF, Inc., I help buyers with financing. You can use one without the other.
For more on pricing this fall, read why Tampa Bay sellers are cutting prices and who has leverage in Pinellas this fall.
Let's plan your sale
If you're thinking about selling, book a consultation. We'll talk about whether a pre-listing inspection makes sense for your home. If you're also buying your next place, you can browse current listings.
Sources: Redfin, "U.S. Pending Home Sales Sink Near 12-Year Low," October 12, 2026; Redfin agent survey, September 2025; Cotality, "10 things to know about the property market: September 2026," September 24, 2026. Figures checked October 30, 2026.
Jonathan Loescher, Tampa Bay Realtor and Mortgage Loan Originator (SL3546365, NMLS 2621894)
Mortgage loans are offered through PMF, Inc., NMLS 1980. Real estate services are offered through Realty of America. They are separate companies, and you don't have to use both. Equal Housing Opportunity. Education only. This is not a commitment to lend. All loans are subject to credit approval, underwriting, and property eligibility. Not all applicants will qualify. Any loan approval is conditional until all underwriting conditions are met. Programs, rates, terms and conditions may change without notice.
Common questions
- Where is Bayou Club in Seminole, Florida?
- Bayou Club Estates is a gated golf community on the Seminole and Largo edge of Pinellas County. Most listings use a Seminole city and ZIP 33777. The gate is off Belcher Road. It is not in Seminole County. Open the Bayou Club homes for sale search for live listings.
- Where is Oakhurst Shores in Seminole, Florida?
- Oakhurst Shores is a west Seminole neighborhood in Pinellas County near Oakhurst Drive, Grove Street, and Boca Ciega Bay. Most sale files use ZIP 33772. It is not in Seminole County. Many homes may have water frontage, however being in this community does not guarantee water frontage. Search live files on the Oakhurst Shores homes for sale page.
- Where is Yacht Club Estates in Seminole, Florida?
- Yacht Club Estates is a Seminole neighborhood in Pinellas County. Listings cluster on streets such as Portside Drive and Commodore Drive in ZIP 33776. It is not Seminole County. The yacht-club name does not guarantee a slip or dock. Search live files on the Yacht Club Estates homes for sale page.
- Are Florida CDD fees mandatory?
- Yes, if the lot is inside the district. You do not opt out because you skip the pool.
- Do CDD fees go away?
- The debt piece can end when the bonds are paid. Operations and maintenance typically does not. Ask the district for the remaining term and a payoff figure. Get it in writing.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.
Have a question about how this applies to your home or loan?
Book a Call