
Homefront Saturday
Homefront Saturday: Is Your Home’s 'Storm Grade' the New Curb Appeal?
Happy Saturday, everyone! Grab a coffee, pull up a chair, and let’s talk shop.
If you’ve been following the market lately: especially here in our beautiful coastal pockets like Tierra Verde or Belleair Beach: you know that the "vibe" of a house is changing. For decades, "curb appeal" was all about the flowers, the fresh coat of paint, and maybe a trendy mailbox. But as we move further into 2026, there’s a new heavy hitter in town that doesn’t care about your choice of hydrangea.
We’re talking about your home’s "Storm Grade."
The industry is seeing a massive push for a standardized rating system that tells buyers exactly how well a house will stand up to Mother Nature’s bad moods. It’s no longer just a "nice-to-have" feature; it’s becoming the gold standard for property value. Today, we’re diving into why "code-plus" is the new luxury and how a high storm rating can actually put money back in your pocket every single month.
What Exactly is a 'Storm Grade'?
Think of a Storm Grade like the sticker on a new car that tells you the MPG, or the energy efficiency rating on your dishwasher. Right now, when you buy a house, you get a thick stack of inspection reports that are, frankly, a bit of a headache to read. A standardized Storm Grade simplifies all that.
It’s a rating: often proposed as a scale from A to F or a tiered system like Bronze, Silver, and Gold: that evaluates structural integrity. It looks at:
- The age and material of the roof.
- The type of window protection (impact glass vs. shutters).
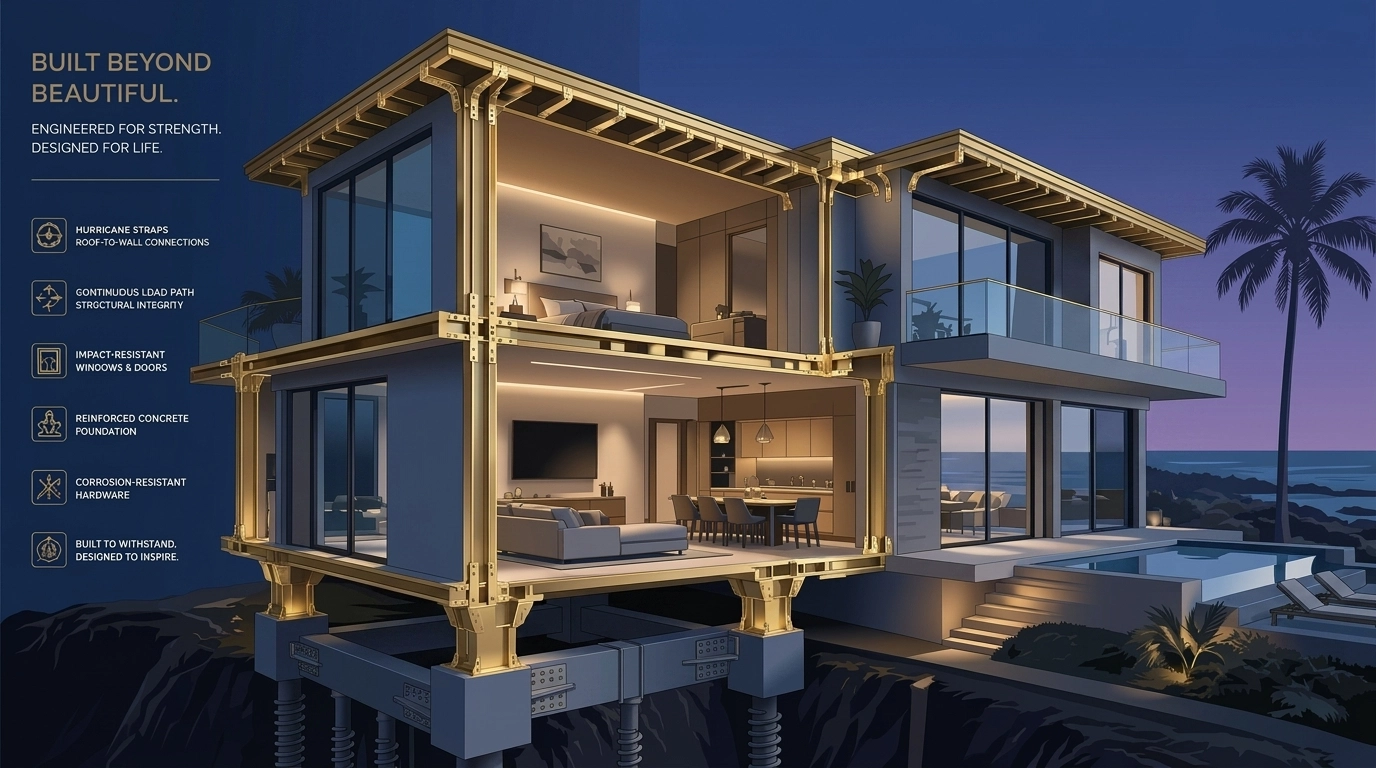
- How the roof is attached to the walls (straps, clips, or the old-school "toenailing").
- Garage door reinforcement.
- The elevation of the property relative to flood zones.
When a buyer sees a "Grade A" resilient home, they aren't just seeing a safe place to live; they’re seeing a lower-risk investment.
Moving Beyond "The Code": The Power of Code-Plus
In the construction world, "Building Code" is essentially the minimum legal requirement to ensure a house doesn't fall down. It’s the "C" grade of the construction world.
"Code-plus" is exactly what it sounds like. It’s builders and homeowners deciding that "good enough" isn't good enough anymore. It means using thicker plywood for the roof deck, installing "Fortified" shingles that won't blow off in a Category 3 hurricane, and ensuring that every joint in the house is reinforced with steel.
Why would someone pay extra for this? Because the market is finally starting to reward it. At Realty of America, we’re seeing that homes built to these higher standards aren't just selling faster: they’re becoming the only homes some buyers are willing to look at.
The Financial Payoff: Insurance and Mortgages
This is where the "educational" part of our brand really kicks in, because the math is pretty spectacular.
1. Insurance Discounts are Real
2. The Rise of Resiliency Mortgage Rates
When you combine lower insurance and a better mortgage rate, the "extra" cost of building to code-plus pays for itself surprisingly fast.
Is Storm Grade Replacing Aesthetics?
I’m not saying you should stop pressure-washing your driveway or skip the landscaping. Curb appeal still gets people through the front door. But in 2026, the "Storm Grade" is what keeps them there and makes them write the check.
Imagine two identical houses in Belleair Beach. One has a stunning designer kitchen but an old roof and standard windows. The other has a slightly dated kitchen but a "Grade A" storm rating with impact glass and a secondary water barrier on the roof.
Five years ago, the designer kitchen won every time. Today? The smart money is moving toward the "Grade A" home. Buyers are realizing that they can remodel a kitchen anytime, but upgrading the entire structural integrity of a house is a much bigger (and more important) lift.
How to Check (or Improve) Your Grade
If you’re thinking about selling: or even if you’re just staying put: knowing where your home stands is vital. Here’s how you can get started:
- Get a Wind Mitigation Inspection: This is the baseline. It tells you exactly how your roof is attached and what your current "grade" would look like to an insurance company.
- Look for the "Weakest Link": Usually, it’s the garage door. Upgrading to a wind-rated garage door is one of the most cost-effective ways to boost your home’s resiliency.
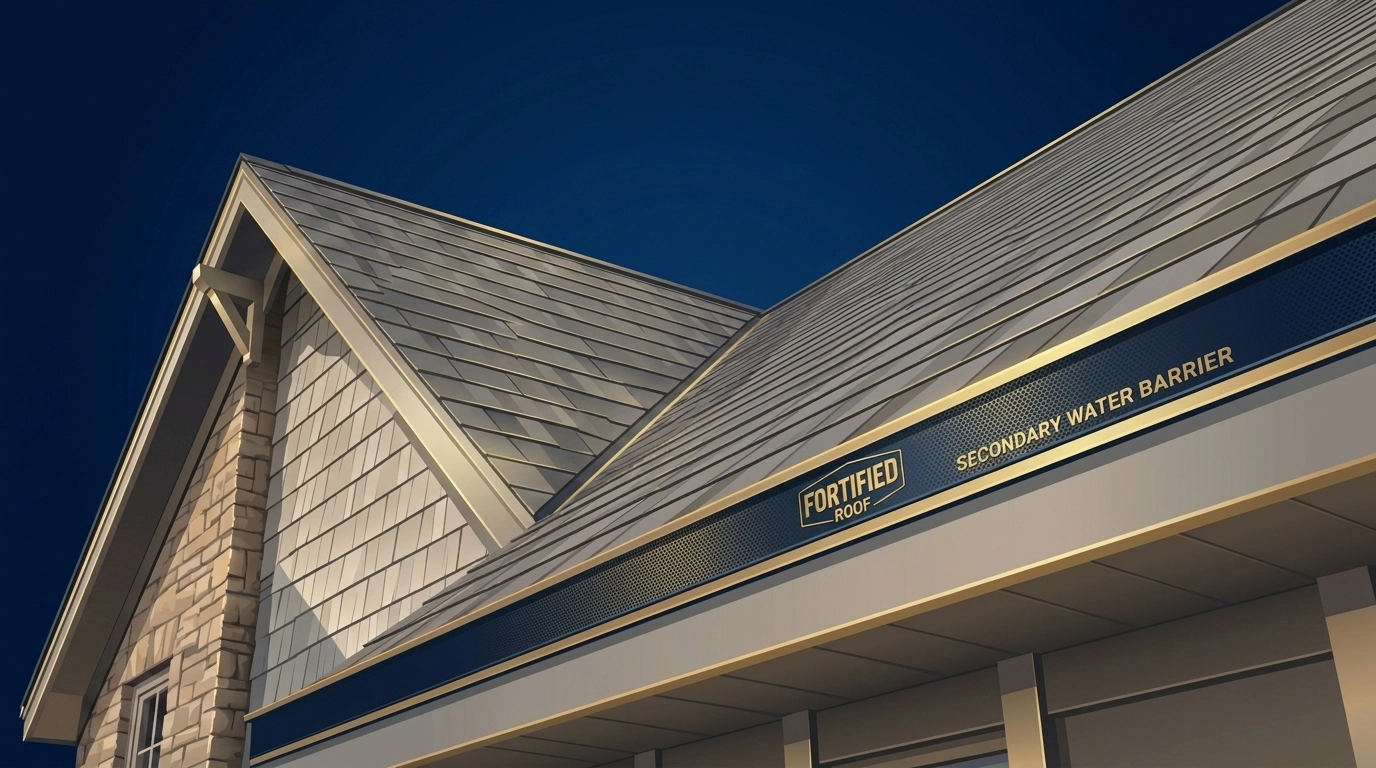
- Seal the Roof: Next time you replace your roof, ask for a "secondary water barrier." It’s a simple tape or membrane that keeps the rain out even if the shingles blow off. It’s a huge factor in Storm Grading.
The Future of Real Estate Listings
I predict that by the end of next year, the "Storm Grade" will be a standard field on every MLS listing, right next to the number of bedrooms and bathrooms. We’re already moving in that direction.
As the Founder of this agency, my goal is to make sure our clients are ahead of the curve. Whether you are buying in Tierra Verde or selling a family home in the suburbs, understanding the value of resiliency is the best way to protect your equity.
If you want to know more about how your home’s specific features might impact your value in today's market, feel free to check out our blog or reach out to us directly. We love talking about this stuff.
Final Thoughts
The "Homefront Saturday" vibe is all about looking at our houses not just as places where we live, but as assets that we need to protect. The shift toward a standardized Storm Grade is a win for everyone. It brings transparency to the buying process, rewards homeowners for making smart upgrades, and helps stabilize our local insurance markets.
So, while you’re out there working on the garden this weekend, take a peek at your roof straps or your window seals. That "Storm Grade" might just be the best investment you ever make.
Stay safe and enjoy the weekend!
: Jonathan Loescher Realtor with Realty of America
Common questions
- When should I shop for home insurance in Florida?
- Shop 45 to 60 days before your renewal. If you're buying, get quotes during your inspection period so you can still walk away if insurance doesn't work. Shop again after a new roof, after wind upgrades, or when you get a nonrenewal notice. Don't wait for a storm. Insurers often pause new policies when a named storm is near Florida.
- What is Zone X vs AE in Tampa Bay flood zones?
- AE is FEMA's high risk zone, with a set base flood elevation. If you finance with a federally backed or regulated lender, flood insurance is required there. X is moderate (shaded) or minimal (unshaded) risk, and flood coverage isn't federally required, though a lender can still ask for it. Both zones flood. Check the lot on the current map and get a quote before you write.
- Do I need a wind mitigation inspection to buy a home in Florida?
- Florida law doesn't require it to buy. It's for insurance. Insurers must offer discounts for wind features, like roof-to-wall straps and protected openings, and the state's uniform form documents them. A completed form is valid for up to five years if the house hasn't changed. Ask the seller for theirs, or order one during your inspection period so the quote reflects the credits.
- What is a 4-point inspection in Florida?
- A 4-point inspection looks at the roof, electrical, plumbing, and HVAC. Insurers use it to decide whether to write a policy on an older home. Each insurer sets its own age cutoff. It isn't a full home inspection or a wind mitigation report. On older Pinellas homes, plan for it during your inspection period so issues show up while you can still negotiate.
- Is flood insurance required in Pinellas County?
- Pinellas County has no blanket rule. Flood insurance is required when the home is in a high risk FEMA zone, like AE or VE, and the mortgage is from a federally regulated or backed lender. A lender can ask for it in other zones too. Cash buyers decide for themselves. Standard homeowners policies don't cover flood, so I get a flood quote on every house.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.