Mortgage Guide
DSCR Loans in Florida: Qualify a Rental on Rent, Not Income
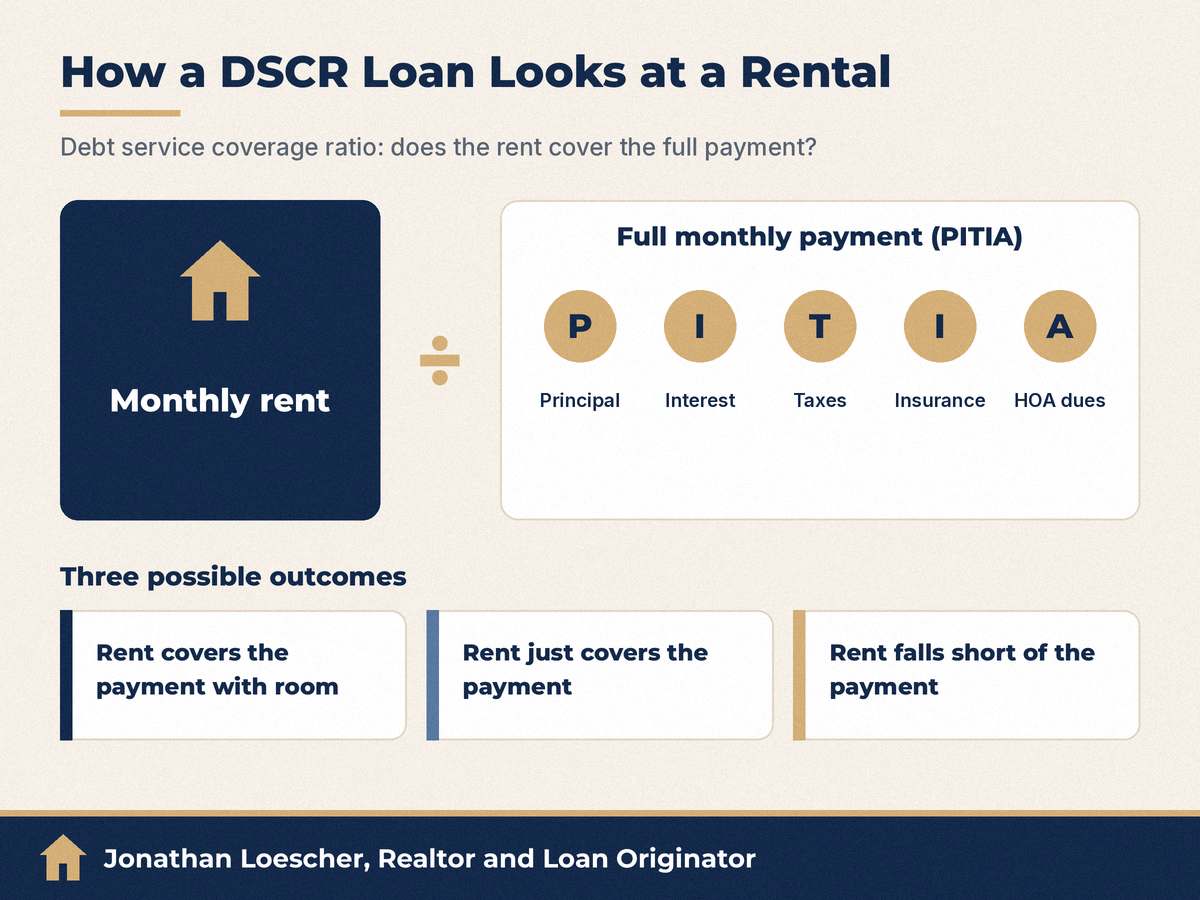
Short answer: Yes. A DSCR (debt service coverage ratio) loan qualifies an investment property mainly on whether its rent covers the full monthly payment, not on your W-2 or tax returns. The payment includes principal, interest, taxes, insurance and any HOA dues. It's for rentals you won't live in, and it usually costs more than a conventional investment loan. Terms vary by lender.
I get this question a lot from Tampa Bay investors. Most of them are self-employed, or they already own a few rentals and their tax returns tell a smaller story than their bank account. A DSCR loan in Florida is one way to finance the next property. Here's how it works, where it fits, and what to check before you buy.
What is a DSCR loan in Florida?
A DSCR loan is a business-purpose mortgage for a non-owner-occupied rental. It's a Non-QM loan, which means it doesn't follow the standard rules Fannie Mae and Freddie Mac use. Instead of proving your personal income, you show that the property can carry itself.
That's useful if you write off a lot on your taxes, earn 1099 income, or have hit the debt-to-income limit on conventional loans. It's not for a home you plan to live in. If that's you, start with my mortgage overview instead.
I offer DSCR loans through PMF, Inc., including loans to LLCs, short-term rentals and condos. We confirm the exact terms at consult.
How is the DSCR calculated? (with a Tampa Bay example)
The math is simple. Divide the monthly rent by the monthly payment.
DSCR = gross monthly rent ÷ PITIA (principal, interest, taxes, insurance and association dues)
Say a house in Pinellas rents for $2,600 a month, and the full payment is $2,300. That's $2,600 ÷ $2,300, or about 1.13. These numbers are hypothetical, for illustration only. They are not a quote or offer.
A ratio above 1 means the rent covers the payment with some room left. A ratio below 1 means it doesn't. Each lender sets its own minimum, and I'll confirm the one that applies to your deal at consult.
Here's the Florida catch. Insurance and HOA dues are part of the payment, and they can move the ratio more than the interest rate does. A house with great rent can still come up short once the insurance quote lands. I've written about that in landlord insurance costs, the landlord insurance spike, Florida HOA fees and flood zones. Get real quotes before you write an offer.
Where does the "rent" number come from?
Lenders typically use one of two sources. The first is the appraiser's market rent estimate. On a single-family home that's often Fannie Mae Form 1007, and on a small multi-unit it's Form 1025. The second is an existing lease, if the property is already rented.
Many DSCR programs accept either one. If there's a lease and a market rent estimate, the underwriter reconciles the two and picks the figure to use. That isn't always the higher number. If the home isn't rented yet, the lender usually goes by the appraiser's estimate. Short-term rentals are handled differently, and I'll cover that below. We'll confirm which rent figure applies to your deal at consult.
DSCR loan requirements: down payment, credit and reserves
DSCR lenders look at the same basic pieces:
- The ratio of rent to payment
- Your credit history
- Your down payment
- Cash reserves left after closing
- A property that's rent-ready and appraises
Each lender sets its own bar for those, and the bars change often. Bring your scenario and we'll confirm the requirements at consult.
What you usually don't need is a stack of tax returns and W-2s. That's the main appeal.
DSCR loan vs. conventional investment-property loan
| Conventional investment loan | DSCR loan | |
|---|---|---|
| How you qualify | Your income and debt-to-income ratio, with tax returns | The property's rent vs. its payment |
| Pricing | Agency pricing, with added costs for investment property | Non-QM, usually priced higher |
| Vesting | Closes in your personal name | Many programs allow an LLC or other entity |
| Number of properties | Agency limits apply | Set by each lender |
| Prepayment penalty | Generally none | Common, and often optional. A shorter penalty or none usually costs more in pricing. Some states limit it. |
A quick way to think about it:
- If your tax returns show strong income and you have room on your debt ratio, conventional is usually cheaper.
- If your returns understate what you earn, or you're at your limit, DSCR may fit better.
- If you want to hold the property in an LLC, DSCR is often the cleaner path.
You can compare financing options or read about the loan programs a Florida Loan Originator can offer.
Can I close a DSCR loan in an LLC?
Often, yes. Many DSCR programs let the loan close in an LLC, and some also allow a corporation or a trust. You'll still be part of the file. The lender will review the people behind the entity, and some programs ask for a personal guarantee. Fannie Mae and Freddie Mac loans generally close to individuals, so this is one of the real differences. We'll confirm the entity and guarantee rules at consult.
I can do LLC DSCR loans through PMF, Inc. How you set up the LLC is a legal and tax question, though. Talk to your attorney or CPA first. This isn't legal or tax advice.
Short-term rentals and DSCR in Pinellas beach towns
Many DSCR programs accept Airbnb and VRBO income. How they count it varies. Some use an appraiser's rent schedule, and others use a third-party short-term rental data report like AirDNA. A few only allow short-term rental income on a refinance, not a purchase. I offer short-term rental DSCR loans, and we'll confirm how your income gets counted at consult.
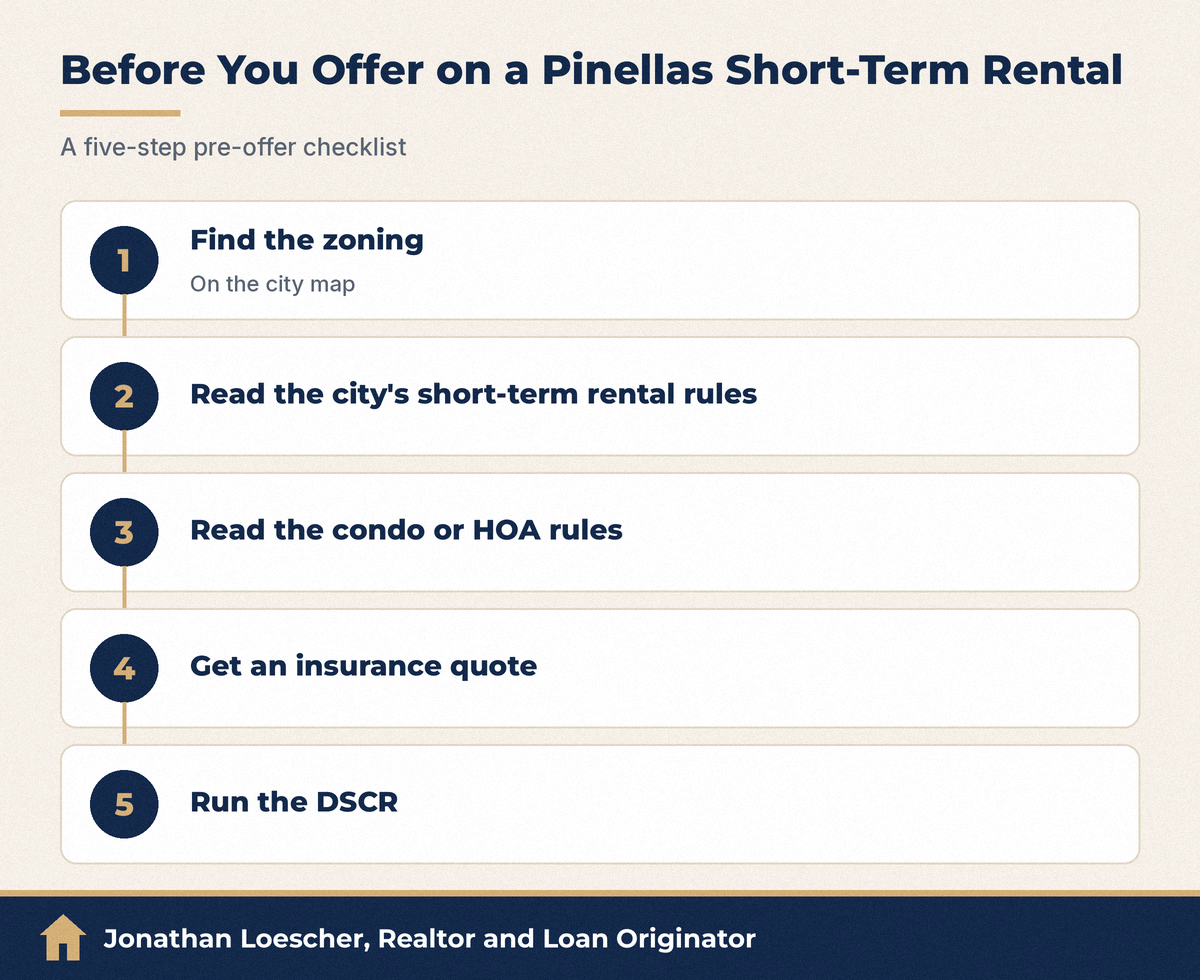
The bigger risk is city rules. A loan doesn't make a rental legal. Each beach city sets its own rules, and they differ a lot. Here's what each city's own website said when I checked on October 22, 2026:
- St. Pete Beach: Stays under one month aren't permitted in many zoning districts. The city allows transient stays of less than 30 days up to 3 times in a 12-month period in the RM district and the Pass-A-Grille Overlay. Monthly rentals are allowed in all residences. (City of St. Pete Beach)
- Treasure Island: Tourist dwellings aren't permitted in the RU-75 or RM-15 districts. They are permitted in CG, RFM-30, RFH-50, PR-MU Core and PR-MU Gulf Boulevard. Owners who rent need a state lodging license and a city Local Business Tax receipt. (City of Treasure Island)
- Madeira Beach: Short-term vacation rentals need a city Business Tax Receipt, a local contact and an annual fire inspection. The city also publishes a vacation rental restriction map. (City of Madeira Beach)
- Indian Rocks Beach: Vacation rentals must register with the city every year under its short-term rental ordinance, along with state, tax and fire inspection requirements. (City of Indian Rocks Beach)
- Clearwater, including Clearwater Beach: The city's page on accessory dwelling units says short-term rentals are not permitted in residential zoning districts, and its business tax brochure asks owners to contact the city before listing a property short term. Ask the city how that applies to your parcel, including on the beach. (City of Clearwater)
Rules change, so check the city again before you buy. Then check the condo or HOA rules too. They can be stricter than the city. My community guides for Treasure Island, Madeira Beach and St. Pete Beach are a good place to start. This isn't legal advice.
Can I use a DSCR loan on a Florida condo?
Yes, and I offer condo DSCR loans. Condos take more homework, though. The lender reviews the building, not just your unit. HOA dues go into the payment, so they hit the ratio directly.
Some buildings don't meet Fannie Mae and Freddie Mac rules. Those are called non-warrantable condos. A number of DSCR programs will still consider them, and a few will look at condotels too. We'll confirm whether your building works at consult.
Florida condos also have newer rules on milestone inspections and reserve studies. A building with big repairs ahead can mean special assessments or a harder review. Plenty of buildings also limit rentals. Read the documents early. I compare the options in duplexes vs high-rise condos.
DSCR features you'll commonly see
Every program is different, but these come up often:
- Closing in an LLC or other entity
- Short-term rental income counted toward the ratio
- Interest-only payment options, with some programs qualifying on the interest-only payment
- Programs that allow rent below the payment, and some no-ratio programs
- Cash-out refinances on rentals you already own
- Room for first-time investors, often with extra conditions
- Programs for foreign national buyers
- A prepayment penalty you can often shorten or skip in exchange for different pricing
Which ones fit your deal depends on the property and your file. We'll confirm them at consult.
Why DSCR loans don't use the ability-to-repay rule
Under federal Regulation Z, credit to buy, improve or maintain a rental property that isn't owner-occupied is treated as business purpose. The CFPB's official commentary says that if the owner expects to live in the property for more than 14 days in the coming year, it can't be treated as non-owner-occupied. (CFPB, Reg Z comment 3(a)-4, checked October 22, 2026)
That's why the lender focuses on the property. It's also why you'll sign a business-purpose and occupancy statement. Be honest on it. Misstating occupancy on a mortgage is fraud.
Costs and trade-offs to ask about
- The rate, which is usually higher than a conventional investment loan
- Prepayment penalties and how they step down
- Whether interest-only payments are an option
- Appraisal and rent schedule fees
- Reserves you'll need after closing
These change with the lender and the market, so we'll go through each one at consult.
How I'd run the numbers with you
I'm a Realtor and Loan Originator, so I can look at both sides of the deal in one sitting. I'll pull rent comps, line up an insurance quote, check the city rules, run the DSCR and walk through your return. My guide to calculating ROI on a Tampa Bay investment property shows how I think about it. If you're an accidental landlord weighing whether to keep a home as a rental, that's worth reading too.
When you're ready, book a consultation. You can also browse properties or apply for a loan.
Programs, ratios, down payments and terms vary by lender and change often. Eligibility is confirmed at application.
Jonathan Loescher, Tampa Bay Realtor and Loan Originator (SL3546365, NMLS 2621894).
Real estate services through Realty of America. Mortgage loans originated through PMF, Inc., NMLS 1980. You don't have to use both. Equal Housing Opportunity. All loan approvals are conditional on lender review. NMLS Consumer Access
Common questions
- Where is Bayou Club in Seminole, Florida?
- Bayou Club Estates is a gated golf community on the Seminole and Largo edge of Pinellas County. Most listings use a Seminole city and ZIP 33777. The gate is off Belcher Road. It is not in Seminole County. Open the Bayou Club homes for sale search for live listings.
- Where is Oakhurst Shores in Seminole, Florida?
- Oakhurst Shores is a west Seminole neighborhood in Pinellas County near Oakhurst Drive, Grove Street, and Boca Ciega Bay. Most sale files use ZIP 33772. It is not in Seminole County. Many homes may have water frontage, however being in this community does not guarantee water frontage. Search live files on the Oakhurst Shores homes for sale page.
- Where is Yacht Club Estates in Seminole, Florida?
- Yacht Club Estates is a Seminole neighborhood in Pinellas County. Listings cluster on streets such as Portside Drive and Commodore Drive in ZIP 33776. It is not Seminole County. The yacht-club name does not guarantee a slip or dock. Search live files on the Yacht Club Estates homes for sale page.
- What is Florida Amendment 3 on the November 2026 ballot?
- Amendment 3 is a proposed Florida Constitution change on the Nov. 3, 2026 ballot. The official title is Increased Homestead Exemption; Lower Cap on Increases in Non-Homestead Property Assessments. It comes from House Joint Resolution 1F. It needs 60% yes. If it passes, it takes effect Jan. 1, 2027. Read the official ballot summary from the Florida Department of State.
- Does Amendment 3 cut school property taxes?
- No. School district taxes are not cut by Amendment 3. The larger homestead exemption is for non-school taxes only. You would still see school taxes under the homestead rules that apply today.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.
Have a question about how this applies to your home or loan?
Book a Call