
Mortgage Guide
USDA Loans Near Tampa Bay, Including Manufactured Homes
A USDA guaranteed loan can be a low-down-payment path for an eligible household buying a primary home in a USDA-eligible rural area, including parts of Pasco and Hernando Counties. Eligibility is address-specific and has to be checked on USDA's official property map. I'm a Mortgage Loan Originator, not an employee of USDA Rural Development, and I'm not acting for USDA.
This article is about the Section 502 Guaranteed Loan Program, which is originated by approved lenders and then guaranteed by USDA. It is not a walkthrough of USDA's staffed direct loan program. Current down payment, income, and property rules are on USDA's official pages, which I reviewed on November 10, 2026. I'm not restating those figures here, because official program terms can change and should be read at the source.
Who is a USDA guaranteed loan for?
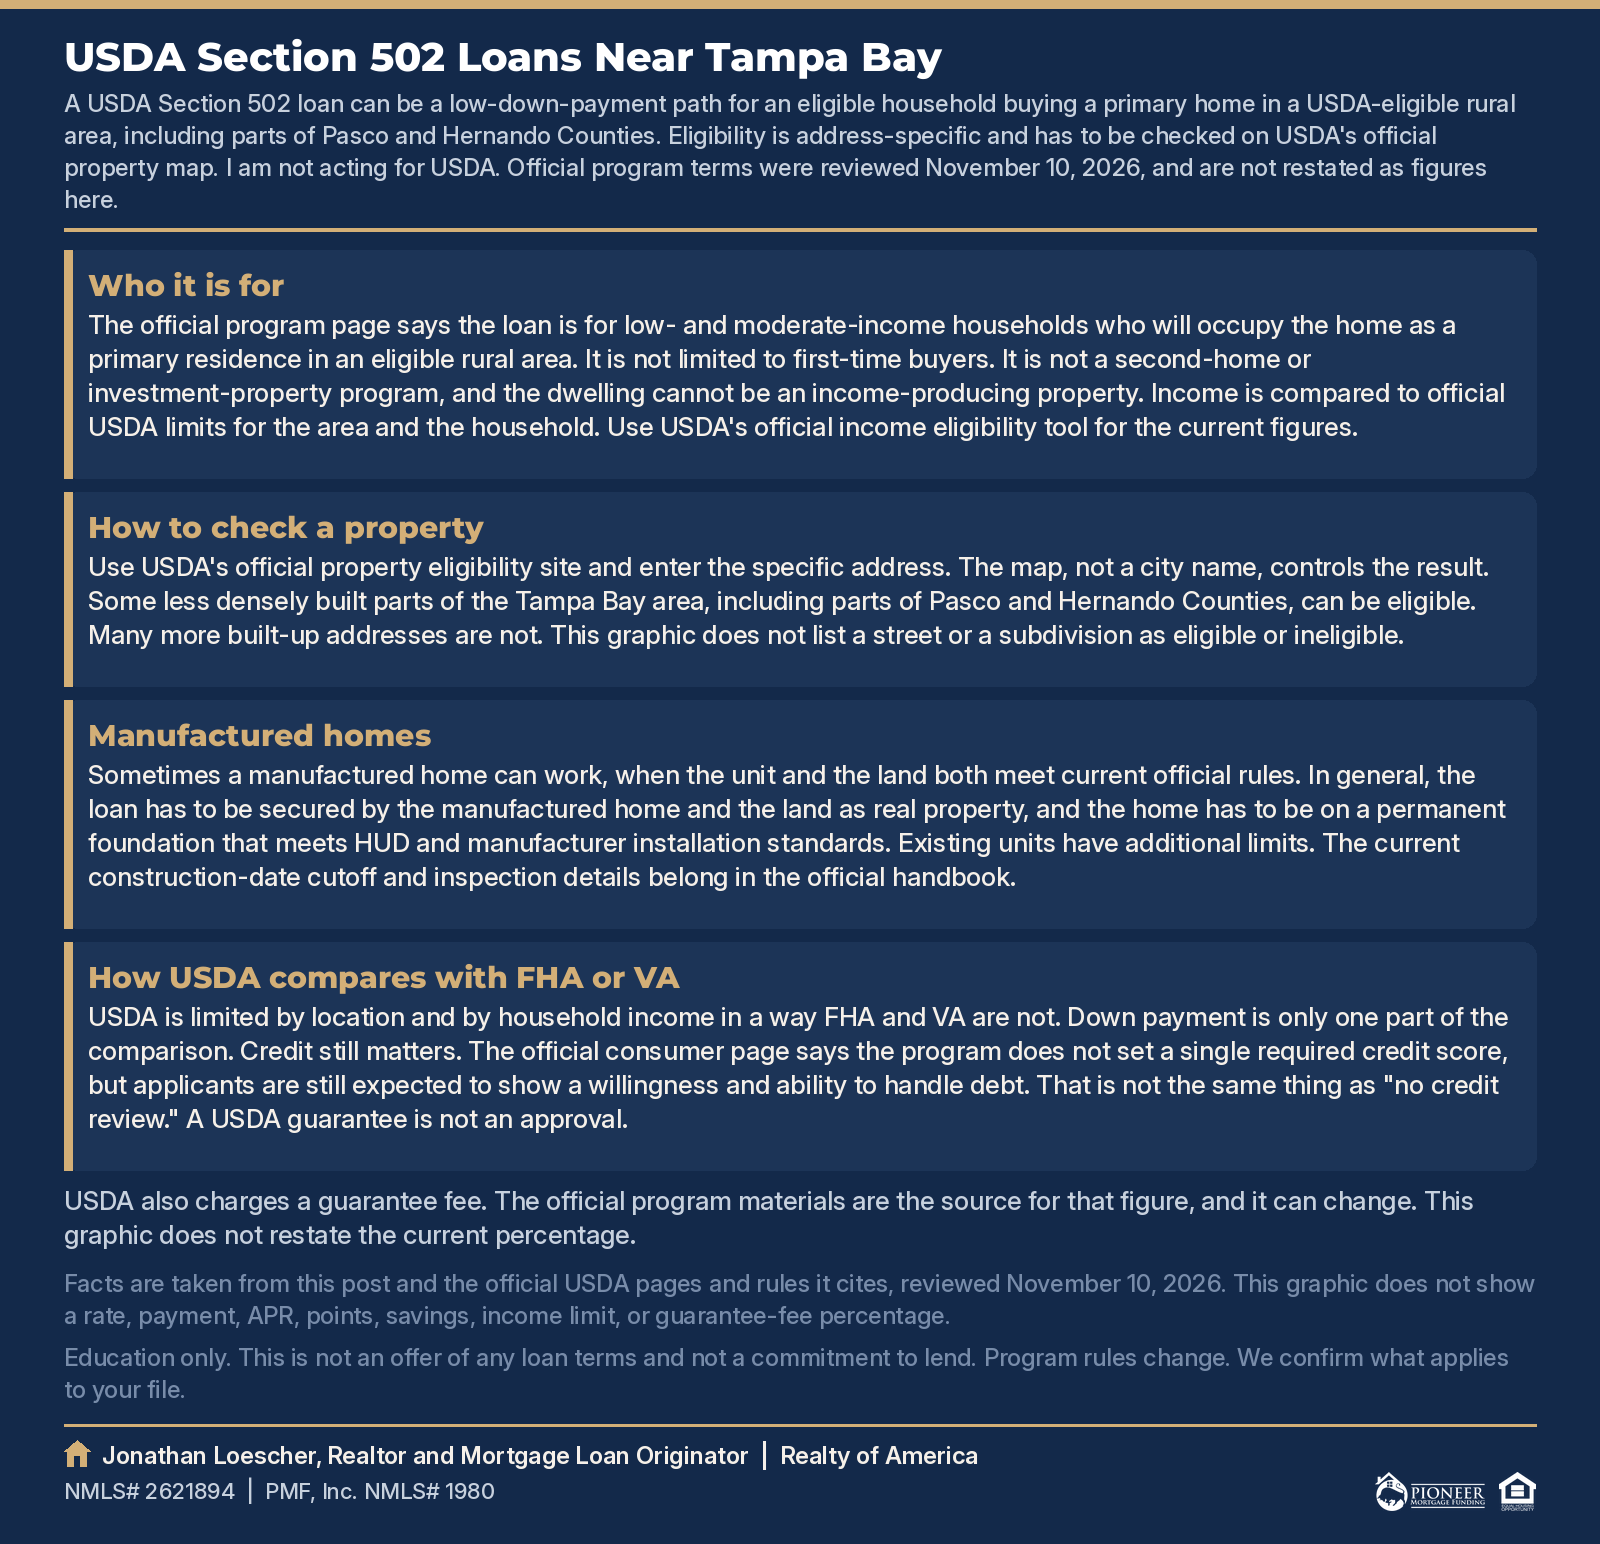
The official program page says the loan is for low- and moderate-income households who will occupy the home as a primary residence in an eligible rural area. It is not limited to first-time buyers. It is not a second-home or investment-property program, and the dwelling cannot be an income-producing property.
Income is compared to official USDA limits for the area and the household. Use USDA's official income eligibility tool for the current figures. I'm not copying a limit or a percentage into this article.
Applicants also have to meet USDA's citizenship or eligible non-citizen rules, which are stated on the official program page. That is a program requirement, not a comment about national origin. I don't give immigration advice.
As of that November 10, 2026 review, the official program page said approved lenders may submit guaranteed-loan applications on an ongoing basis during the federal fiscal year. Processing and funding can still change, so recheck the official page rather than treating this article as a status update.
How do you check if a Tampa Bay property is eligible?
Use USDA's official property eligibility site and enter the specific address. The map, not a city name, controls the result. Some less densely built parts of the Tampa Bay area, including parts of Pasco and Hernando Counties, can be eligible. Many more built-up addresses are not. I won't list a street or a subdivision as eligible or ineligible in this article, because the official map can change and the answer is parcel-specific.
If you later assume an existing USDA loan, official rules can allow that assumption even if the area has since ceased to be rural. That is a different question, covered in assumable mortgages in Florida.
Can a manufactured home work with a USDA loan?
Sometimes, when the unit and the land both meet current official rules. USDA's regulation at 7 CFR 3555.208, including the January 3, 2025 amendment, and HB-1-3555 Chapter 13, set those rules. I reviewed the regulation on November 10, 2026.
In general, the loan has to be secured by the manufactured home and the land as real property, and the home has to be on a permanent foundation that meets HUD and manufacturer installation standards. New units have construction, installation, and warranty requirements. Existing units have additional limits, including construction date, foundation certification, and whether the home has been moved from another site. The current construction-date cutoff and the inspection details belong in the official handbook, not in a summary that could go stale.
This is a loan-program article. It is not a housing-type guide to manufactured homes in a particular city.
How does USDA compare with FHA or VA?
USDA is limited by location and by household income in a way FHA and VA are not. FHA has its own property, credit, and down-payment rules, which I walk through in FHA loan requirements in Florida. VA has its own entitlement and occupancy rules; start with VA loan programs if that benefit applies to you.
Down payment is only one part of the comparison. For a plain-language look at cash to close, see how much down payment you need in Florida. If you are starting from a first-home search rather than a program name, the first-time buyer path is a better place to start.
A newly built home in an eligible area can still bring other Florida costs, including a Community Development District assessment. See what a CDD is and buying a newly built home.
What else should you expect on a USDA file?
The home has to be a modest, safe primary residence that meets program property standards. Official materials say detached, attached, condo, PUD, modular, and manufactured homes can be considered when they otherwise qualify. Condo and PUD approval is still a file-level question.
USDA also charges a guarantee fee. I'm not restating the current percentage here. The official program materials are the source for that figure, and it can change.
Credit still matters. The official consumer page says the program does not set a single required credit score, but applicants are still expected to show a willingness and ability to handle debt. That is not the same thing as "no credit review."
A USDA guarantee is not an approval, and I cannot promise that a specific property or household will qualify. If this looks like the right program, we check the official map, the official income tool, and the property type against the current handbook.
Common questions
Do I have to be a first-time buyer for a USDA loan?
No. The guaranteed program is not limited to first-time buyers. You do have to occupy the home as your primary residence and meet the other official eligibility rules.
Is every part of Pasco or Hernando eligible?
No. Parts of those counties can be eligible, and parts are not. Enter the address on USDA's official property eligibility site.
Can I use USDA for a second home or a rental?
No. This guaranteed program is for a primary residence, and the dwelling cannot be an income-producing property.
If you want to see whether a USDA guaranteed loan may fit, you can start a loan application. If you want to talk through an address and a household first, book a consultation.
This article is for education only. It is not an offer of any loan terms and not a commitment to lend. Program rules change. We confirm what applies to your file.
Jonathan Loescher, Realtor, Florida real estate license SL3546365, Realty of America. Jonathan Loescher, Mortgage Loan Originator, NMLS 2621894. Mortgage loans are originated through PMF, Inc., NMLS 1980, a Florida licensed Mortgage Broker. Real estate and mortgage services are provided by separate companies, and you don't have to use both. Verify licensing at www.nmlsconsumeraccess.org. Equal Housing Opportunity.
Education only. This is not a commitment to lend. All loans are subject to credit approval, underwriting, and property eligibility. Not all applicants will qualify. Any loan approval is conditional until all underwriting conditions are met. Programs, rates, terms and conditions may change without notice.
Common questions
- What is the average mortgage rate in Florida today?
- I don't post averages here. Rates move often, and your rate depends on your credit, loan program, down payment, property type, occupancy, and lock period. A published average can be far from what you'd get. Ask for a quote on your own scenario, dated, with the program and terms. Any loan approval is conditional until all underwriting conditions are met.
- How often do mortgage rates change?
- Often. Pricing can change daily, sometimes more than once, as bond markets move. Your quote also changes if your credit, down payment, program, or property changes. That's why quotes are dated. A rate lock holds pricing for a set period once you're under contract. Any loan approval is conditional until all underwriting conditions are met.
- What is a rate lock?
- A rate lock holds your rate and pricing for a set number of days while your loan closes. If the market rises, your lock holds. If closing slips past it, an extension may cost extra. Longer locks can cost more. Changes to your file, like the price or credit, can reprice it. Any loan approval is conditional until all underwriting conditions are met.
- What is the difference between pre-approval and pre-qualification?
- Pre-qualification is a conversation about income and credit. Pre-approval is a lender review of a file. Apply on this site for a second look even if you already have a letter from somewhere else.
- What Florida mortgage loan programs can a Mortgage Loan Originator offer?
- Common programs include conventional, FHA, VA, cash-out refinance, and non-QM loans like bank statement and DSCR. Some pair with down payment assistance. The right one depends on your file. You don't have to use both companies. Any loan approval is conditional until all underwriting conditions are met.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.