
Mortgage Guide
What VA Tidewater Means If the Appraisal May Come in Short
VA Tidewater is a step in the VA appraisal process. If the appraiser thinks the value may come in below the contract price, the appraiser notifies the lender (or the point of contact on the appraisal request) before finishing the report. The parties then have a short window to send in additional comparable sales. It does not require the appraiser to hit the contract price, and it does not promise that the value or the closing date will change.
I get this question from veteran buyers, and from the Realtors representing them, when a Tampa Bay contract is already in motion. For VA loan basics, see How do VA loans work in Pinellas County? The name sounds like a coastal Florida rule. It isn't. VA first piloted the procedure in the Tidewater area of Virginia, and it now applies to VA purchase appraisals nationwide.
What is the Tidewater procedure?
The official source is the VA Lender's Handbook (Pamphlet 26-7), Chapter 10, Topic 8, "Market Data Submitted During the Appraisal Process."
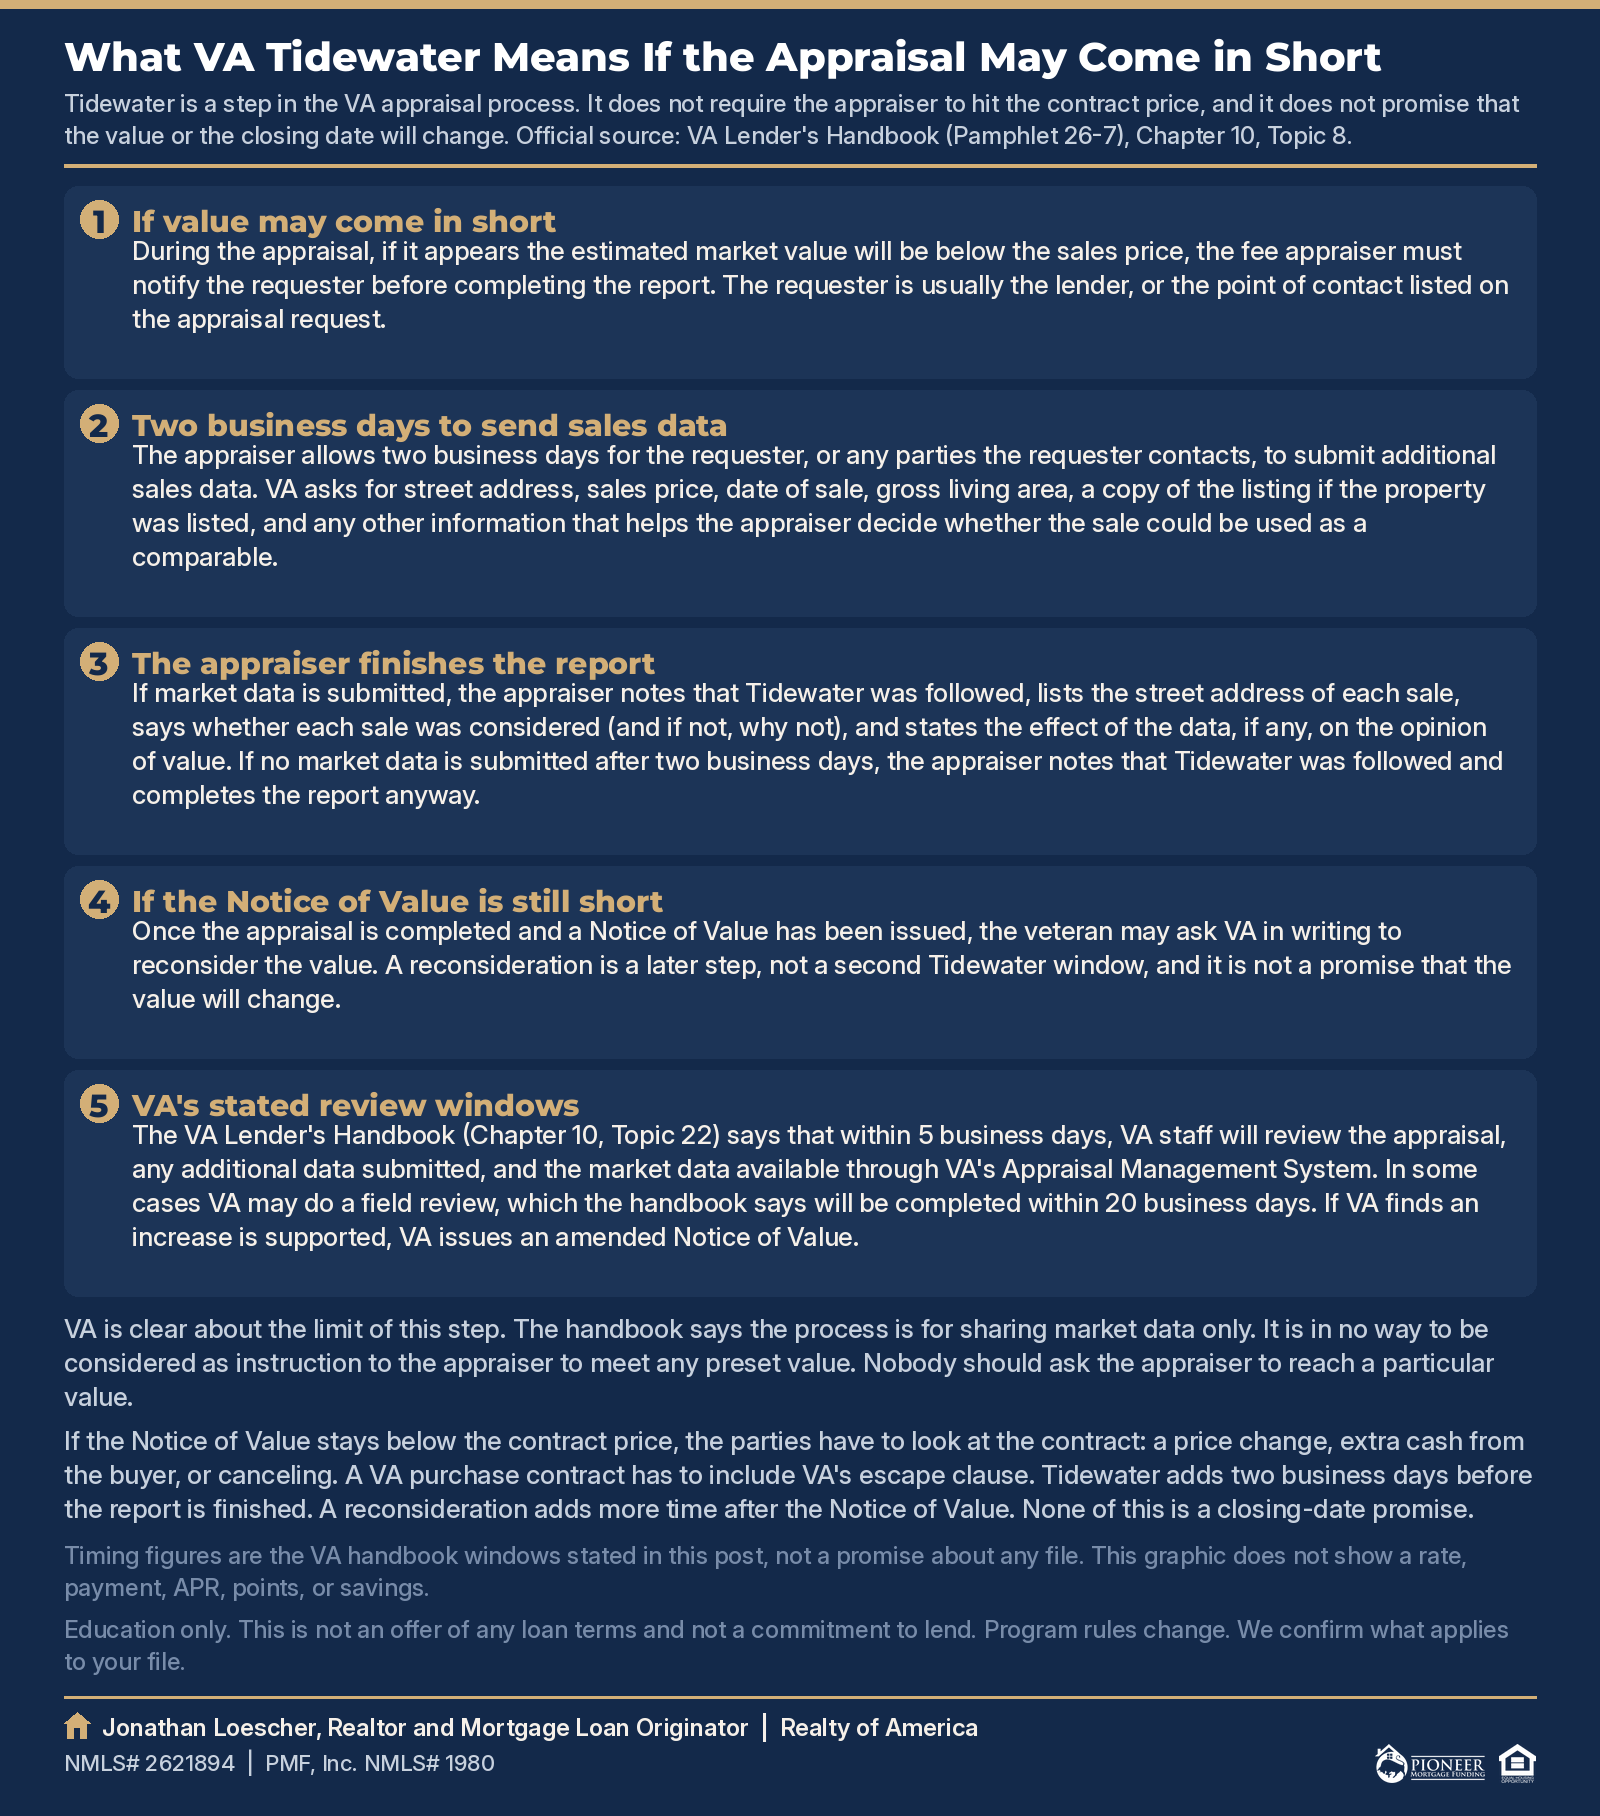
During the appraisal, if it appears the estimated market value will be below the sales price, the fee appraiser must notify the requester before completing the report. The appraiser then allows two business days for the requester, or any parties to the transaction the requester contacts, to submit additional sales data they want considered.
VA is clear about the limit of this step. The handbook says the process is for sharing market data only. It is in no way to be considered as instruction to the appraiser to meet any preset value.
What should you send in those two business days?
For each potential comparable sale, VA asks for:
- Street address
- Sales price
- Date of sale
- Gross living area
- If the property was listed, a copy of the listing with details about the property
- Any other information that helps the appraiser decide whether the sale could be used as a comparable
It's the requester's job to provide enough information for the appraiser to analyze. Closed sales, with enough detail to compare to the subject, are what help. A list of addresses with no prices or dates usually doesn't.
Two business days is short, especially if you're coordinating between a buyer, a listing office, and a lender in Pinellas or Hillsborough. If we already think value may be tight, I like to have a focused set of closed comps ready before the appraiser calls. The Realtor usually pulls those sales, and they go to the appraiser through the lender or the point of contact on the appraisal request. Nobody should ask the appraiser to reach a particular value. That is preparation, not a promise about value.
What does the appraiser do with the data?
If market data is submitted, the appraiser notes in the appraisal that Tidewater was followed. The appraiser lists the street address of each sale submitted, says whether each sale was considered (and if not, why not), and states the effect of the data, if any, on the opinion of value.
If no market data is submitted after two business days, the appraiser notes that Tidewater was followed and completes the report anyway. The clock does not stay open until someone finds a better sale.
What if the value still comes in short after Tidewater?
Once the appraisal is completed and a Notice of Value has been issued, the veteran may ask VA in writing to reconsider the value. The request goes to VA's Regional Loan Center and can be sent through the lender. Closed comparable sales, which your Realtor can help gather, are encouraged but not required. The VA Lender's Handbook (Chapter 10, Topic 22) says that within 5 business days, VA staff will review the appraisal, any additional data submitted, and the market data available through VA's Appraisal Management System. In some cases VA may do a field review, which the handbook says will be completed within 20 business days. If VA finds an increase is supported, VA issues an amended Notice of Value.
A reconsideration is a later step, not a second Tidewater window. It also is not a promise that the value will change. If the Notice of Value stays below the contract price, the parties have to look at the contract: a price change, extra cash from the buyer, or canceling. A VA purchase contract has to include VA's escape clause, which lets the veteran cancel without losing the earnest money deposit if the price is above VA's reasonable value, or choose to go forward anyway. The contract and its deadlines control the details, so review them with your Realtor and, if needed, a Florida real estate attorney.
None of this is a closing-date promise. Tidewater adds two business days before the report is finished. A reconsideration adds more time after the Notice of Value. Build some room into the contract when you can. How long does it take to buy a home in Pinellas County? is a useful companion on overall timing. For a wider view of cash to close if the price or loan amount changes, see How Much Are Closing Costs in Florida?.
How I can help
I'm a Realtor, and I'm also a Mortgage Loan Originator. On a VA purchase, I can help you leave a realistic appraisal window in the contract, gather comparable sales quickly if Tidewater is invoked, and talk through the next step if the Notice of Value still comes in short. PMF, Inc. is a mortgage broker that works with many wholesale lenders, so I can compare options for your situation. Rates and terms vary by lender, program and borrower, and I can't promise any particular rate or approval. They are separate companies, and you don't have to use both.
If you're already under contract and the appraisal is in motion, book a consultation or, if we need the loan file open, apply for a loan.
Common questions
Does Tidewater mean the appraiser has to meet the contract price?
No. VA says the process is for sharing market data only. The appraiser's opinion of value is still the appraiser's opinion of value.
Who gets the Tidewater call?
The appraiser notifies the requester, or the point of contact listed on the appraisal request. That is usually the lender, and it can be another contact the lender designates. The two-business-day clock starts with that notice.
Is Tidewater only used in Florida?
No. It started as a pilot in the Tidewater area of Virginia. It is now a VA purchase-appraisal procedure, including here in Tampa Bay.
This article is for education only. It is not an offer of any loan terms and not a commitment to lend. Program rules change. We confirm what applies to your file.
Jonathan Loescher, Realtor, Florida real estate license SL3546365, Realty of America. Jonathan Loescher, Mortgage Loan Originator, NMLS 2621894. Mortgage loans are originated through PMF, Inc., NMLS 1980, a Florida licensed Mortgage Broker. Real estate and mortgage services are provided by separate companies, and you don't have to use both. Verify licensing at www.nmlsconsumeraccess.org. Equal Housing Opportunity.
Education only. This is not a commitment to lend. All loans are subject to credit approval, underwriting, and property eligibility. Not all applicants will qualify. Any loan approval is conditional until all underwriting conditions are met. Programs, rates, terms and conditions may change without notice.
Common questions
- How do I start buying a home in Tampa Bay?
- Start with a consult and a pre-approval. Pick two or three areas, sign a buyer agreement, and tour. Get insurance quotes early. I'm a Realtor and, separately, a licensed Mortgage Loan Originator with PMF, Inc. Those are two separate companies, and you don't have to use both. Any loan approval is conditional until all underwriting conditions are met.
- What are the first-time home buyer steps in Tampa Bay?
- Check your budget and credit. Get pre-approved and ask about down payment assistance. Sign a buyer agreement, tour homes, and make an offer. Inspect and get insurance quotes. Clear your loan conditions and close. File homestead after you move in. Any loan approval is conditional until all underwriting conditions are met.
- How much are closing costs in Florida for a buyer?
- It depends on your price, loan, and contract. Buyers usually pay loan fees, appraisal, the lender's title policy, settlement and recording fees, and Florida's doc stamp and intangible taxes on the new mortgage. Prepaids add homeowners insurance, escrow for taxes, and interest. Your Loan Estimate shows them. Cash buyers skip the mortgage taxes and loan fees.
- What is earnest money in Florida?
- Earnest money is your good faith deposit after an accepted offer. It's held in escrow and credited at closing. The contract sets when it's due and when you can cancel and get it back, such as during the inspection period or under a financing contingency. Miss a deadline, and it can be at risk. Confirm wiring instructions by phone.
- How does the Florida buyer-broker agreement work after NAR?
- Compensation is negotiated in writing. It is not automatic that the seller pays. I will walk the buyer-broker agreement with you before you tour. Do not assume buyers pay nothing.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.