Buying
Pinellas Home Insurance 2026: Wind Mitigation, Roof Age, Flood
When buyers call me about a house in Pinellas, the first question is usually the price. The second one should be the insurance. In a lot of homes here, the insurance bill changes the monthly payment as much as the rate does.
The good news is a few things about a house drive most of that bill, and you can check them before you write an offer. Here's what I look at.
Why insurance hits harder in Pinellas
Pinellas is a peninsula. A big share of it sits low and close to the water, and the 2024 storms reminded everyone of that. Helene pushed storm surge into homes along the Gulf beaches and the bay in late September 2024, and Milton followed in October with heavy rain and wind.
So you're really shopping for two policies. The homeowners policy covers wind and most other damage. Flood is a separate policy. Your homeowners policy doesn't cover flood, even when a hurricane causes it, and Florida law makes insurers print that warning on the declarations page of any policy without flood coverage.
Wind mitigation: the discount most buyers miss
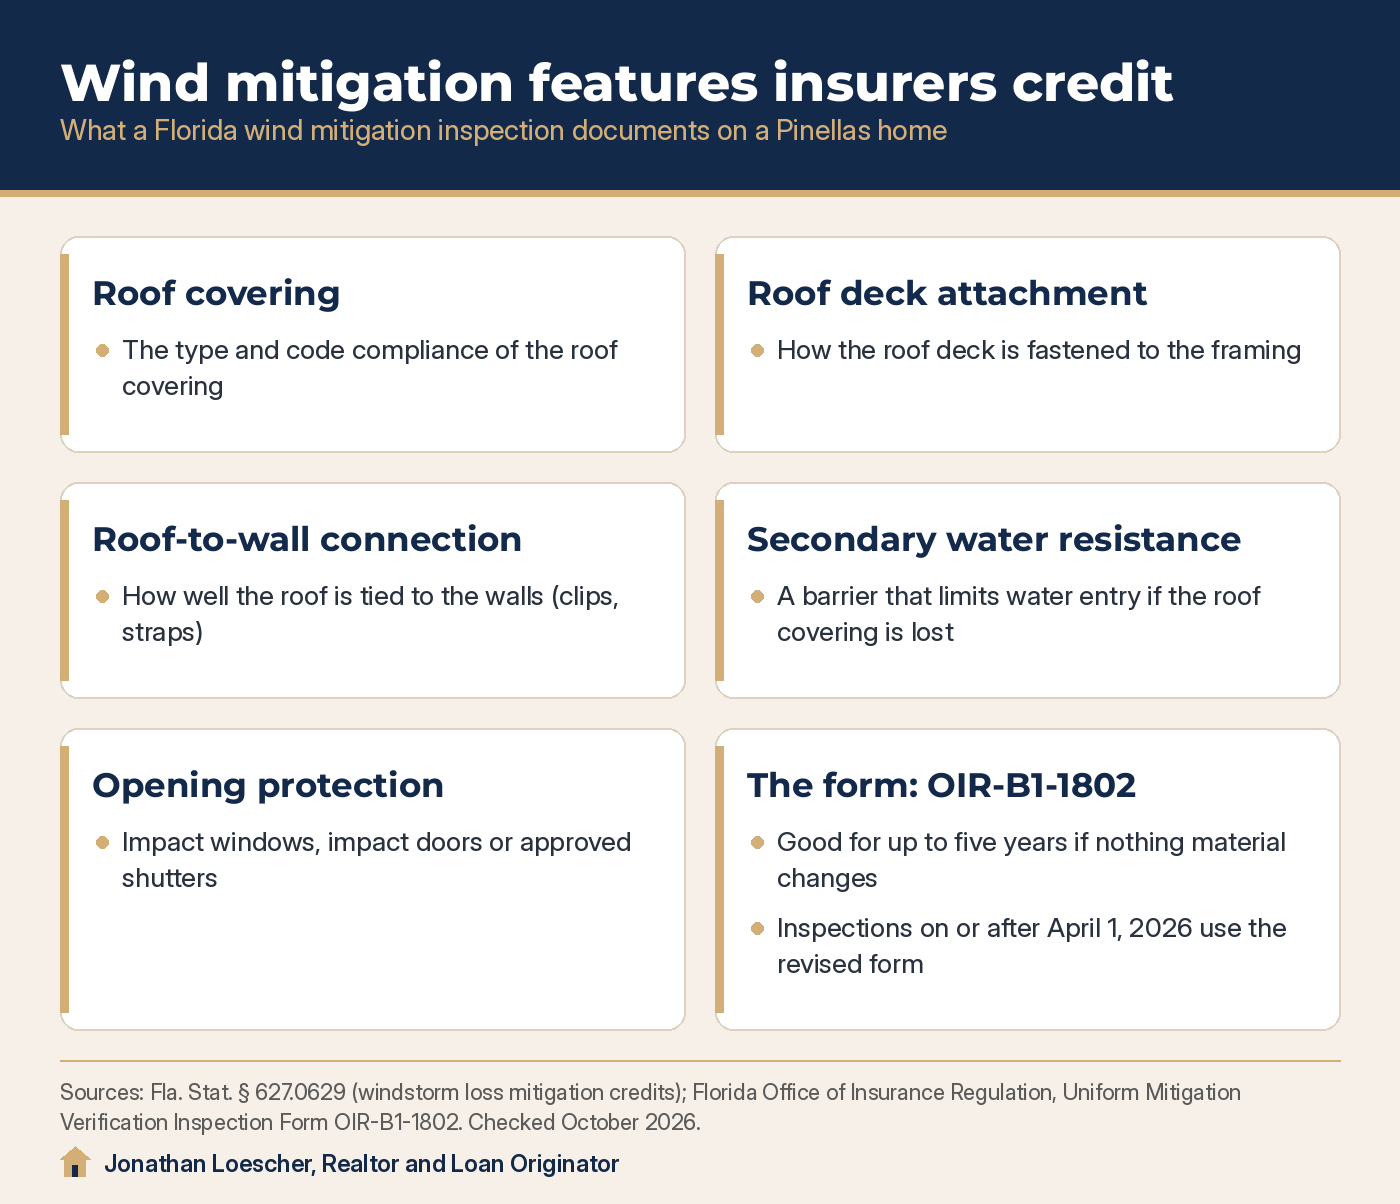
Florida law requires insurers to give discounts or credits for features that cut windstorm losses. Section 627.0629 of the Florida Statutes lists the kinds of features that count, like roof-to-wall strength, roof covering, secondary water resistance, and opening protection such as impact windows or shutters.
The way you prove those features is a wind mitigation inspection on the state's form, OIR-B1-1802. The Office of Insurance Regulation says a completed form can be used for up to five years, as long as nothing material has changed on the house. Inspections done on or after April 1, 2026 use the revised version of the form.
Here's how I use that as a buyer's agent:
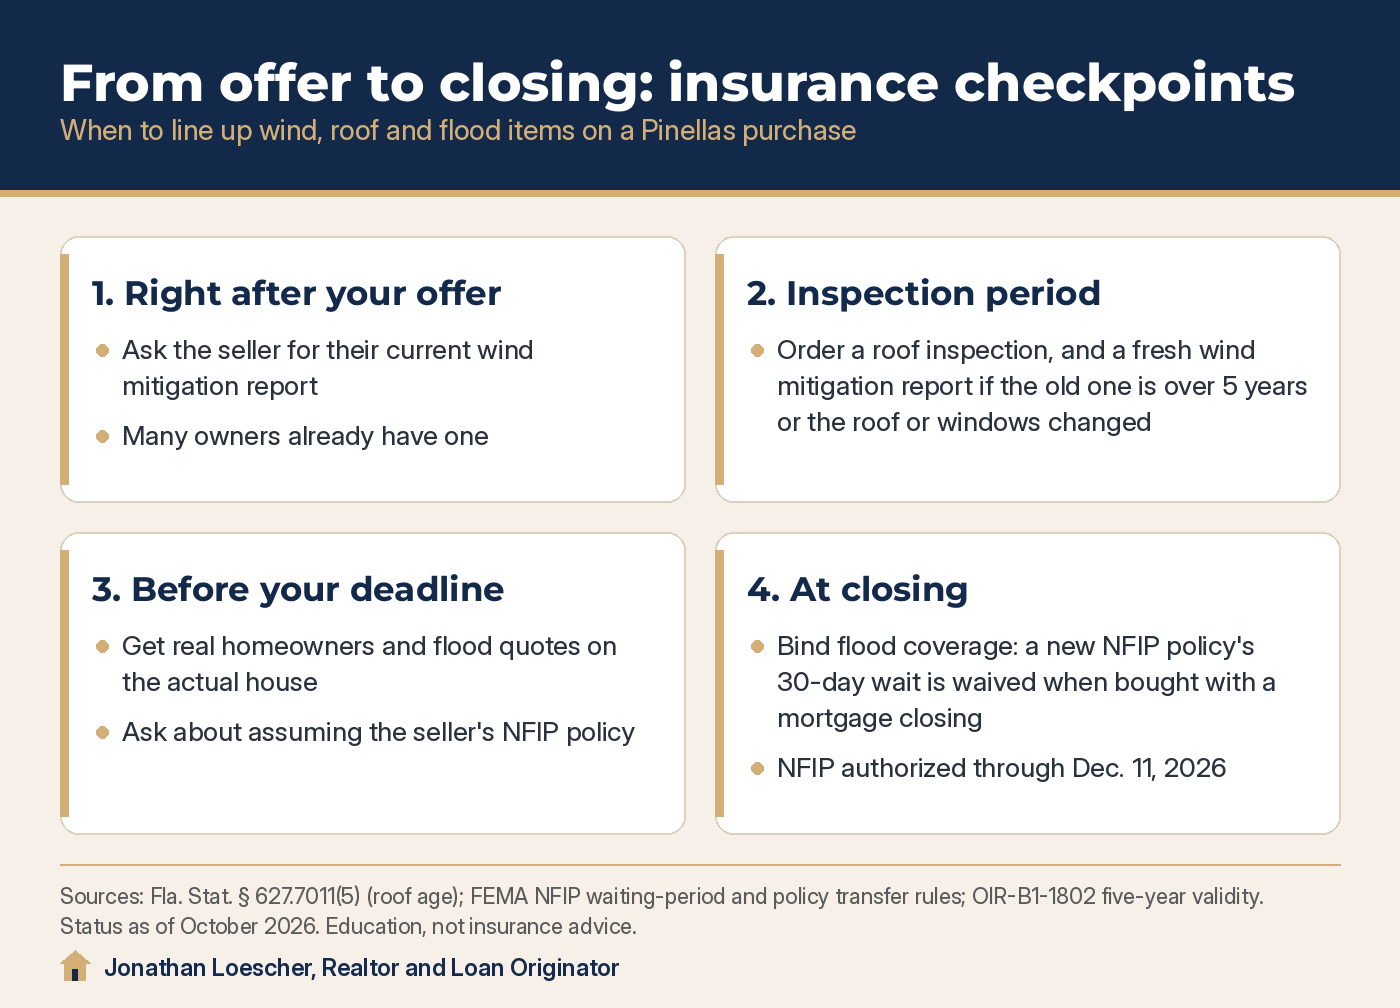
- Ask the seller for their current wind mitigation report early. Many owners already have one.
- If it's older than five years, or there's been a new roof or new windows since, get a fresh one during your inspection period.
- Send it to the insurance agent quoting you. Don't assume the credits carry over on their own.
I walk through what the inspection itself looks like in my post on the 4-point and wind mitigation inspections.
Roof age: what the law says
Roof age is the thing that kills the most quotes I see. Florida law gives you some protection here, and you should know exactly what it says.
Under section 627.7011(5), an insurer can't refuse to write or renew a homeowners policy just because of roof age if the roof is less than 15 years old. If the roof is 15 or older, the insurer has to let you get an inspection by an authorized inspector, at your cost, before it can require a new roof. If that inspection shows at least five years of useful life left, the insurer can't refuse you based on age alone. The rule applies to policies issued or renewed on or after July 1, 2022.
A few things to keep in mind. The law says "solely because of the age of the roof." An insurer can still decline for condition or other underwriting reasons. And the roof's age is counted from the last time the whole roof surface was replaced, so a patch job doesn't reset the clock.
My reading for buyers: a roof in its late teens isn't a deal breaker, but it's a negotiating point. Get the roof inspected inside your inspection period and get a real quote before your deadline.
Flood insurance: three rules to know before you close
The 30-day wait. A new NFIP flood policy generally has a 30-day waiting period. There's an exception when the policy is bought in connection with a mortgage closing, so most buyers can have coverage start at closing. Still, don't wait until the last week to shop it.
The transfer option. Under FEMA's Risk Rating 2.0 pricing, increases for primary residences are generally capped at 18% a year until a policy reaches its full-risk rate. FEMA also lets a seller's existing NFIP policy transfer to the buyer. If the seller has an older policy on a glide path, ask about assuming it. It can be cheaper than starting fresh.
Citizens now requires flood. If you end up with Citizens Property Insurance for wind, flood coverage is being phased in as a condition of coverage. Homes in a FEMA special flood hazard area already need it. Outside those zones, it's tied to dwelling value, and by January 1, 2027, it applies to Citizens personal residential policies with wind coverage regardless of value. Condo unit-owner and tenant policies are exempt.
One more date to watch. The NFIP runs on short-term extensions from Congress. As of this writing it's authorized through December 11, 2026. If it lapsed, existing policies would stay in force, but new and renewal NFIP policies couldn't be written until Congress acted. If you're closing in December, I'd line up flood coverage early.
If you're not sure what flood zone a house is in, start with my guide to Florida flood zones or the county's map at floodmaps.pinellas.gov.
My Safe Florida Home can lower the bill after you move in
If you buy a single-family home or townhouse and claim your homestead exemption, you may qualify for the state's My Safe Florida Home program. It offers a free hurricane mitigation inspection. Homes built before January 1, 2008, with an insured value of $700,000 or less, may then qualify for a matching grant. The state pays $2 for every $1 you put in, up to $10,000. Low-income homeowners can get up to $10,000 with no match. You have to be approved before work starts. Condos, rentals and second homes aren't eligible.
I covered the program in more detail in this earlier post. Check mysafeflhome.com for current funding before you count on it.
How this fits into your loan
Your homeowners and flood premiums usually go into escrow, so they show up in your monthly payment. When I run numbers with buyers, I want a real quote on the real house, not an estimate. That's the only way the payment is honest.
If you'd like to walk through a specific house, book a consultation. When you're ready to finance, you can apply for a loan. You can work with me on the real estate side, the loan side, or both.
This is general education, not insurance advice. Talk to a licensed insurance agent about your own coverage.
Jonathan Loescher, Tampa Bay Realtor and Loan Originator (SL3546365, NMLS 2621894).
Real estate services through Realty of America. Mortgage loans originated through PMF, Inc., NMLS 1980. You don't have to use both. Equal Housing Opportunity. All loan approvals are conditional.
Common questions
- Where is Bayou Club in Seminole, Florida?
- Bayou Club Estates is a gated golf community on the Seminole and Largo edge of Pinellas County. Most listings use a Seminole city and ZIP 33777. The gate is off Belcher Road. It is not in Seminole County. Open the Bayou Club homes for sale search for live listings.
- Where is Oakhurst Shores in Seminole, Florida?
- Oakhurst Shores is a west Seminole neighborhood in Pinellas County near Oakhurst Drive, Grove Street, and Boca Ciega Bay. Most sale files use ZIP 33772. It is not in Seminole County. Many homes may have water frontage, however being in this community does not guarantee water frontage. Search live files on the Oakhurst Shores homes for sale page.
- Where is Yacht Club Estates in Seminole, Florida?
- Yacht Club Estates is a Seminole neighborhood in Pinellas County. Listings cluster on streets such as Portside Drive and Commodore Drive in ZIP 33776. It is not Seminole County. The yacht-club name does not guarantee a slip or dock. Search live files on the Yacht Club Estates homes for sale page.
- How do VA loans work in Pinellas County?
- I originate VA loans in Pinellas County through PMF, Inc. for eligible veterans, active-duty service members, and surviving spouses. Many files can close with zero down and no monthly PMI. A funding fee may apply unless you are exempt. Eligibility is confirmed at consult. This is not a promise of approval. PMF, Inc. is not acting on behalf of or at the direction of the VA.
- Should I sell before I buy in Tampa Bay?
- Sell-first is the simpler calendar. If you must close the next Pinellas home before the current one funds, ask about sell-before-you-buy. That is a lender convenience path with a 2.25 percent program fee, not a brokerage commission. I can model both as Realtor and as MLO. We confirm the file at consult.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.
Have a question about how this applies to your home or loan?
Book a Call