
Mortgage Guide
P&L-Only Loans and Other Self-Employed Mortgage Paths in Tampa Bay
If you work for yourself in Tampa Bay, there may be more than one way to document your income for a mortgage. The question is which documentation path fits the way your income actually shows up. A P&L-only loan uses a professionally prepared profit and loss statement to figure income. Other paths use bank statements, 1099s, a written verification of employment, full tax returns, or assets. The right one is the one that qualifies you accurately, at a cost that makes sense for your file.
If deposits are the cleaner story, start with how bank statement loans work and the short version, How does a bank statement loan work? This post is the comparison, including P&L-only, so you don't have to stitch those options together yourself.
What is a P&L-only loan?
It's usually a Non-QM mortgage. That means it isn't a "qualified mortgage" under federal ability-to-repay rules, and it doesn't follow the documentation standards Fannie Mae and Freddie Mac use for a regular conventional loan. The lender still has to make a reasonable, good-faith determination, based on verified records, that you can repay. The main income document is a profit and loss statement for the business.
Guidelines vary by lender and change. On files I see, the P&L is usually prepared by a CPA or a licensed tax preparer, not filled out by the borrower alone. It covers a limited number of months, often a year or two, though the exact period depends on the program. Some programs also ask for a letter from that same preparer. Cash reserves after closing are commonly required. Ask me what applies to your file.
The "only" in P&L-only means the P&L is the income test, without using bank statements as the main way to calculate income. You will still provide other standard loan documents, such as identification, a credit authorization, and asset statements to show down payment and reserves.
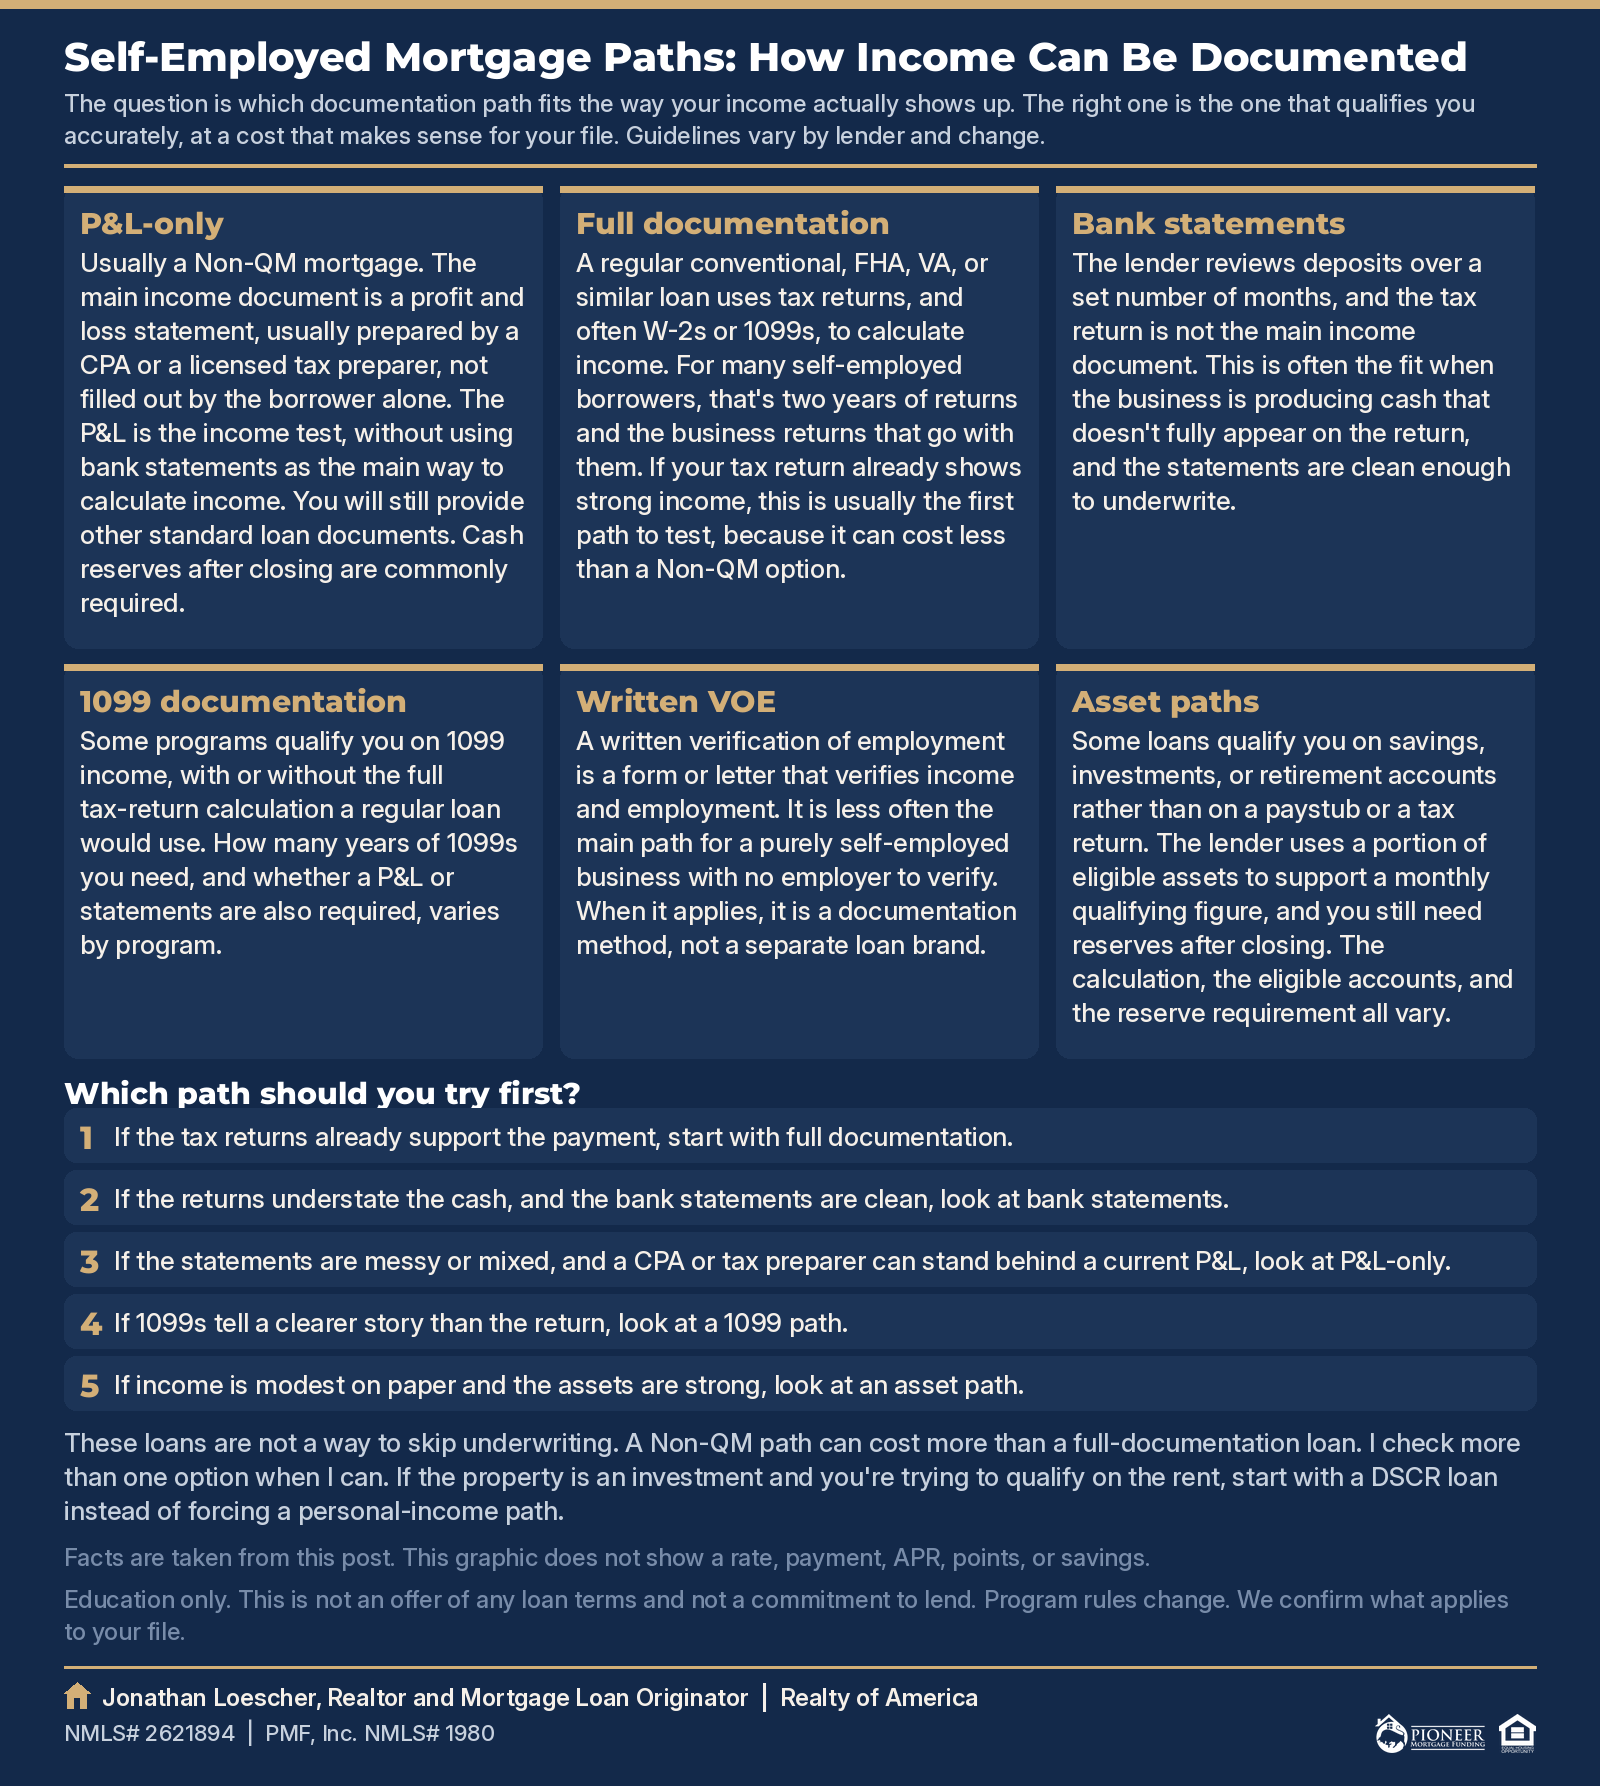
How do the other self-employed paths compare?
Full documentation. A regular conventional, FHA, VA, or similar loan uses tax returns, and often W-2s or 1099s, to calculate income. For many self-employed borrowers, that's two years of returns and the business returns that go with them. Write-offs that help you at tax time can shrink the income a regular loan can count. That's the problem many business owners in Pinellas and Hillsborough run into. If your tax return already shows strong income, this is usually the first path I test, because it can cost less than a Non-QM option.
Bank statements. The lender reviews deposits over a set number of months, and the tax return is not the main income document. I explain who that helps, what you can buy with it, and how the process works in Self-Employed in Tampa Bay? How Bank Statement Loans Work. This is often the fit when the business is producing cash that doesn't fully appear on the return, and the statements are clean enough to underwrite.
1099 documentation. Some programs qualify you on 1099 income, with or without the full tax-return calculation a regular loan would use. This can fit consultants, contract workers, and others who are paid on 1099s. How many years of 1099s you need, and whether a P&L or statements are also required, varies by program. I confirm the documentation on your file rather than assuming a 1099 stack is enough by itself.
Written verification of employment. A written VOE is a form or letter that verifies income and employment. It can help some files that have an employer, a contract, or a pay history that isn't complete on paystubs alone. It is less often the main path for a purely self-employed business with no employer to verify. When it applies, it is a documentation method, not a separate loan brand. Guidelines vary, and we confirm whether a written VOE helps your file.
Asset paths. Some loans qualify you on savings, investments, or retirement accounts rather than on a paystub or a tax return. The lender uses a portion of eligible assets to support a monthly qualifying figure, and you still need reserves after closing. There are agency versions of this idea and Non-QM versions. The calculation, the eligible accounts, and the reserve requirement all vary. If this is the path that fits, I'll walk through the current method on your file. If you're comparing options at a high level, Can I get a mortgage without tax returns in Tampa Bay? is a useful short answer.
A rental, not a home to live in. If the property is an investment and you're trying to qualify on the rent, start with DSCR Loans in Florida instead of forcing a personal-income path.
Which path should you try first?
I don't pick a product first and then make the file fit it. I look at how your income shows up, then compare.
- If the tax returns already support the payment, start with full documentation.
- If the returns understate the cash, and the bank statements are clean, look at bank statements.
- If the statements are messy or mixed, and a CPA or tax preparer can stand behind a current P&L, look at P&L-only.
- If 1099s tell a clearer story than the return, look at a 1099 path.
- If income is modest on paper and the assets are strong, look at an asset path.
These loans are not a way to skip underwriting. The lender still has to be able to support the income figure and the rest of the file. Approvals stay conditional. A Non-QM path can cost more than a full-documentation loan. I check more than one option when I can. You can also compare programs on Financing and in What Florida mortgage loan programs can a Mortgage Loan Originator offer?
What else do these programs usually look at?
Credit, down payment, the property, and reserves still matter. Condos, townhomes, and one-to-four unit homes can fit on some programs, including some buildings that don't meet standard agency condo rules. Terms vary. Occupancy can be a primary home, and on some programs a second home or a rental. I'll confirm what your file and the property can use.
It may not fit if you don't have the records the path requires, if the business is too new for the program's time period, or if a cheaper full-documentation loan already works. Newer businesses have fewer options. Bring what you have and I'll tell you whether a path is even on the table.
How does the process work?
- Apply for a mortgage and tell me you're self-employed.
- Gather the records you already have: tax returns, bank statements, 1099s, and any CPA-prepared P&L.
- I compare the paths and tell you which one shows your income best.
- You get a pre-approval that matches the way we actually qualified the file, so what you show sellers is accurate.
How Realty of America and PMF fit together
As a Realtor with Realty of America, I can help you find the home. As a Mortgage Loan Originator with PMF, Inc., I can help with the loan. You can use one or both. You don't have to use both.
Want to talk through the documentation first? Book a consultation.
Common questions
Can I prepare the P&L myself?
Most P&L-only programs want it prepared by a CPA or a licensed tax preparer. I wouldn't count on a self-prepared spreadsheet. We'll confirm the documentation standard for your file.
Is a P&L-only loan always cheaper than using bank statements?
No. Sometimes it's the only path that fits. Sometimes bank statements or full documentation cost less. I run more than one option when I can.
Do I have to pick one path before I apply?
No. Bring the records you have. I'll tell you which path, or combination of reviews, is worth running on your file.
This article is for education only. It is not an offer of any loan terms and not a commitment to lend. Program rules change. We confirm what applies to your file.
Jonathan Loescher, Realtor, Florida real estate license SL3546365, Realty of America. Jonathan Loescher, Mortgage Loan Originator, NMLS 2621894. Mortgage loans are originated through PMF, Inc., NMLS 1980, a Florida licensed Mortgage Broker. Real estate and mortgage services are provided by separate companies, and you don't have to use both. Verify licensing at www.nmlsconsumeraccess.org. Equal Housing Opportunity.
Education only. This is not a commitment to lend. All loans are subject to credit approval, underwriting, and property eligibility. Not all applicants will qualify. Any loan approval is conditional until all underwriting conditions are met. Programs, rates, terms and conditions may change without notice.
Common questions
- What is the average mortgage rate in Florida today?
- I don't post averages here. Rates move often, and your rate depends on your credit, loan program, down payment, property type, occupancy, and lock period. A published average can be far from what you'd get. Ask for a quote on your own scenario, dated, with the program and terms. Any loan approval is conditional until all underwriting conditions are met.
- How often do mortgage rates change?
- Often. Pricing can change daily, sometimes more than once, as bond markets move. Your quote also changes if your credit, down payment, program, or property changes. That's why quotes are dated. A rate lock holds pricing for a set period once you're under contract. Any loan approval is conditional until all underwriting conditions are met.
- What is a rate lock?
- A rate lock holds your rate and pricing for a set number of days while your loan closes. If the market rises, your lock holds. If closing slips past it, an extension may cost extra. Longer locks can cost more. Changes to your file, like the price or credit, can reprice it. Any loan approval is conditional until all underwriting conditions are met.
- What is the difference between pre-approval and pre-qualification?
- Pre-qualification is a conversation about income and credit. Pre-approval is a lender review of a file. Apply on this site for a second look even if you already have a letter from somewhere else.
- What Florida mortgage loan programs can a Mortgage Loan Originator offer?
- Common programs include conventional, FHA, VA, cash-out refinance, and non-QM loans like bank statement and DSCR. Some pair with down payment assistance. The right one depends on your file. You don't have to use both companies. Any loan approval is conditional until all underwriting conditions are met.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.