
Mortgage Guide
The New Appraisal Report (UAD 3.6) and Your Closing Timeline
On November 2, 2026, Fannie Mae and Freddie Mac made a new appraisal format, Uniform Appraisal Dataset 3.6, mandatory for new conventional appraisal reports submitted to their Uniform Collateral Data Portal. The report itself changed. The fact that many loans still need an appraisal did not. This can affect how long an appraisal takes to land in your file, especially this fall and winter, but it does not come with a new closing-date promise.
If you're under contract in Pinellas, Hillsborough, or a nearby county on a conventional loan, this is the format change your appraiser and lender are working through right now.
What is UAD 3.6?
UAD is the standardized dataset appraisers use so a residential appraisal can be sent electronically to Fannie Mae and Freddie Mac through the Uniform Collateral Data Portal, or UCDP. Version 3.6 is a redesign of that dataset and of the Uniform Residential Appraisal Report.
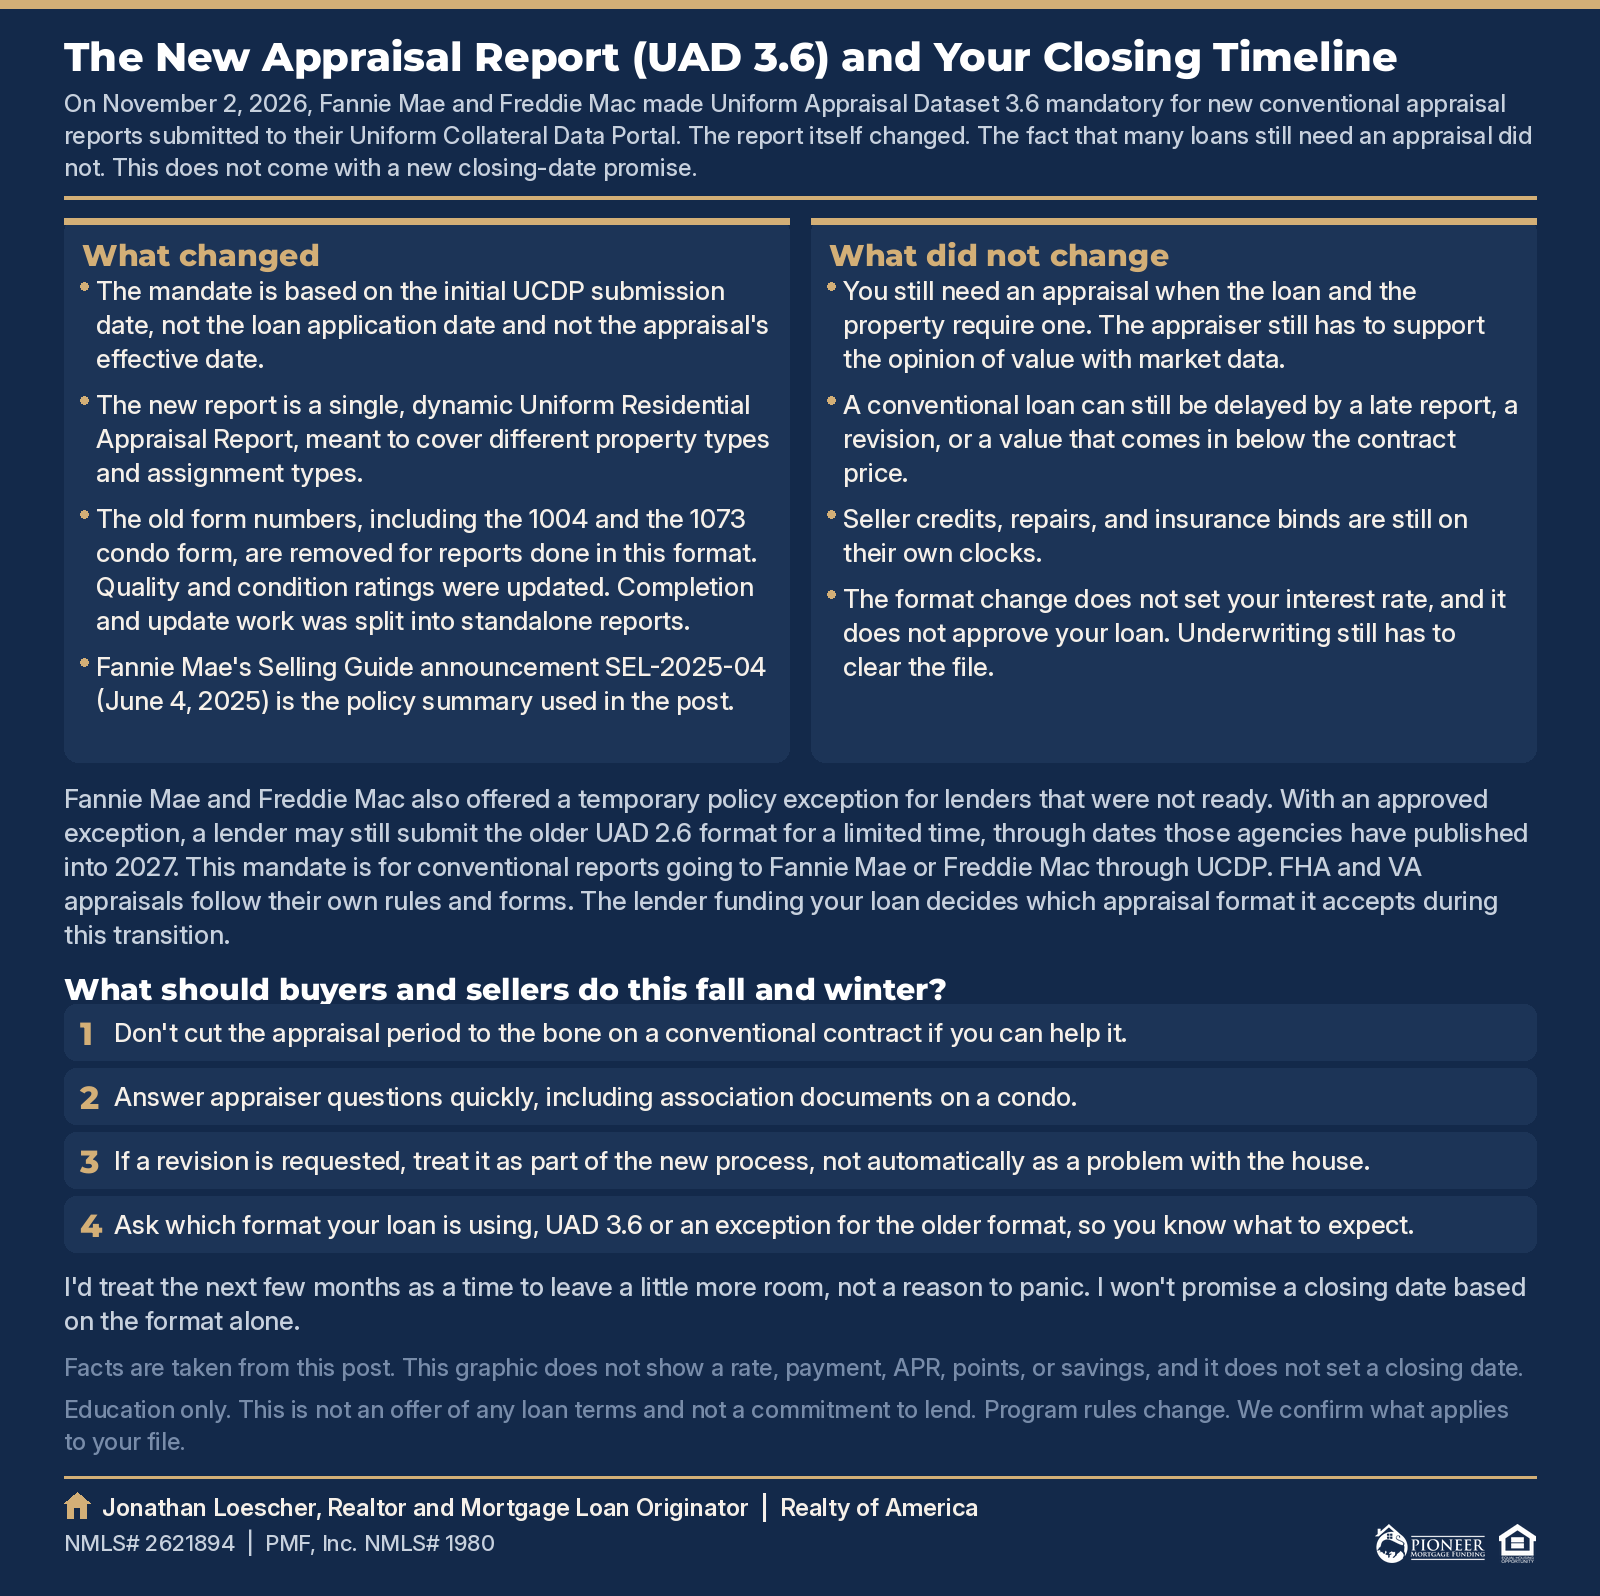
Fannie Mae's Selling Guide announcement SEL-2025-04 (June 4, 2025) is the policy summary I use with clients. The new report is a single, dynamic Uniform Residential Appraisal Report. It is meant to cover different property types (a one-unit house, a condo, a manufactured home) and different assignment types (a traditional interior inspection, a desktop, or a hybrid). The old form numbers, including the 1004 and the 1073 condo form, are removed for reports done in this format. Quality and condition ratings were updated. Completion and update work was split into standalone reports.
In plain terms: the appraiser is still giving an opinion of value. The container the opinion arrives in is new, and more of the detail is structured data instead of a long free-form addendum.
When did it start, and does every loan use it?
The mandate is based on the initial UCDP submission date, not the loan application date and not the appraisal's effective date. New conventional appraisal reports submitted to UCDP on or after November 2, 2026, are supposed to use UAD 3.6.
Fannie Mae and Freddie Mac also offered a temporary policy exception for lenders that were not ready. With an approved exception, a lender may still submit the older UAD 2.6 format for a limited time, through dates those agencies have published into 2027. That exception does not change the appraiser's long-term move to the new format. It does mean two files in the same neighborhood, in the same month, might not look the same.
This mandate is for conventional reports going to Fannie Mae or Freddie Mac through UCDP. FHA and VA appraisals follow their own rules and forms. We confirm what your loan type actually needs.
What did not change?
You still need an appraisal when the loan and the property require one. The appraiser still has to support the opinion of value with market data. A conventional loan can still be delayed by a late report, a revision, or a value that comes in below the contract price. Seller credits, repairs, and insurance binds are still on their own clocks. The format change does not cancel any of that.
It also does not set your interest rate, and it does not approve your loan. Underwriting still has to clear the file.
How can this affect a closing timeline?
I'd treat the next few months as a time to leave a little more room, not a reason to panic. Appraisers, appraisal management companies, and lenders are all using a new report structure. That can mean extra questions, a revision, or a slower turn while someone in the chain gets used to the new fields. It can also go smoothly. I won't pretend I can predict which way your file will go.
If your lender, or the investor it sells to, is still on an approved exception and using the older format, the report may look familiar, with its own cutoff dates later on. Which format a file uses can differ from one lender to the next. The lender funding your loan decides which appraisal format it accepts during this transition, so we confirm it once your loan is placed. If your lender is on UAD 3.6, you may see a different-looking report than a neighbor who closed last year. Either way, the contract still needs a realistic appraisal deadline and a realistic closing date. For a wider view of purchase timing, see How long does it take to buy a home in Pinellas County? If you want a refresher on the cost side of the closing, see How Much Are Closing Costs in Florida? For inspection timing that often runs alongside the appraisal, see Florida Home Inspection, 4-Point, and Wind Mitigation.
What should buyers and sellers do this fall and winter?
- Don't cut the appraisal period to the bone on a conventional contract if you can help it.
- Answer appraiser questions quickly, including association documents on a condo.
- If a revision is requested, treat it as part of the new process, not automatically as a problem with the house.
- Ask which format your loan is using, UAD 3.6 or an exception for the older format, so you know what to expect.
How I can help
I'm a Realtor, and I'm also a Mortgage Loan Originator. I can help you set a realistic appraisal and closing window in the contract, and once your loan is placed with a lender, I can tell you which appraisal format that lender is using so the timeline isn't a surprise. PMF, Inc. is a mortgage broker that works with many wholesale lenders, so I can compare options for your situation. Rates and terms vary by lender, program and borrower, and I can't promise any particular rate or approval. They are separate companies, and you don't have to use both.
If you're already under contract, book a consultation. When you need the loan started, apply for a loan.
Common questions
Does UAD 3.6 change how much my home is worth?
No. It changes how the appraisal is structured and submitted. The value is still the appraiser's opinion, supported by the market data in the report.
Did this start on November 2, 2026 for every appraisal?
It started on that date for new conventional reports submitted to UCDP, unless the lender has an approved temporary exception to keep using the older format for a limited time. FHA and VA files follow their own rules.
Will my closing be delayed?
It might take longer than a routine file did a year ago, or it might not. I won't promise a closing date based on the format alone. We plan the contract with some room and stay on top of the appraisal once it's ordered.
This article is for education only. It is not an offer of any loan terms and not a commitment to lend. Program rules change. We confirm what applies to your file.
Jonathan Loescher, Realtor, Florida real estate license SL3546365, Realty of America. Jonathan Loescher, Mortgage Loan Originator, NMLS 2621894. Mortgage loans are originated through PMF, Inc., NMLS 1980, a Florida licensed Mortgage Broker. Real estate and mortgage services are provided by separate companies, and you don't have to use both. Verify licensing at www.nmlsconsumeraccess.org. Equal Housing Opportunity.
Education only. This is not a commitment to lend. All loans are subject to credit approval, underwriting, and property eligibility. Not all applicants will qualify. Any loan approval is conditional until all underwriting conditions are met. Programs, rates, terms and conditions may change without notice.
Common questions
- How do I start buying a home in Tampa Bay?
- Start with a consult and a pre-approval. Pick two or three areas, sign a buyer agreement, and tour. Get insurance quotes early. I'm a Realtor and, separately, a licensed Mortgage Loan Originator with PMF, Inc. Those are two separate companies, and you don't have to use both. Any loan approval is conditional until all underwriting conditions are met.
- What are the first-time home buyer steps in Tampa Bay?
- Check your budget and credit. Get pre-approved and ask about down payment assistance. Sign a buyer agreement, tour homes, and make an offer. Inspect and get insurance quotes. Clear your loan conditions and close. File homestead after you move in. Any loan approval is conditional until all underwriting conditions are met.
- How much are closing costs in Florida for a buyer?
- It depends on your price, loan, and contract. Buyers usually pay loan fees, appraisal, the lender's title policy, settlement and recording fees, and Florida's doc stamp and intangible taxes on the new mortgage. Prepaids add homeowners insurance, escrow for taxes, and interest. Your Loan Estimate shows them. Cash buyers skip the mortgage taxes and loan fees.
- What is earnest money in Florida?
- Earnest money is your good faith deposit after an accepted offer. It's held in escrow and credited at closing. The contract sets when it's due and when you can cancel and get it back, such as during the inspection period or under a financing contingency. Miss a deadline, and it can be at risk. Confirm wiring instructions by phone.
- How does the Florida buyer-broker agreement work after NAR?
- Compensation is negotiated in writing. It is not automatic that the seller pays. I will walk the buyer-broker agreement with you before you tour. Do not assume buyers pay nothing.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.