
Mortgage Guide
DSCR Loan Pros and Cons for Florida Investors
A DSCR loan can qualify a rental on its rent, not on your personal income, but it has tradeoffs. That flexibility can help when tax returns or a personal debt ratio would get in the way. It can also cost more than an agency investment loan, and it does not guarantee the rent you will collect. If you want the definition and the occupancy rules, start with DSCR Loans in Florida. This post is about the tradeoffs. It does not rewrite that guide.
What a DSCR loan is, in one short reminder
Debt service coverage looks at the rental's income against the rental's monthly housing payment, often written as principal, interest, taxes, insurance, and association dues. These are typically business-purpose loans on investment property. Loans made mainly for a business purpose generally fall outside the ability-to-repay rule. Expect to sign a statement that the property is for business use and that you won't live in it, and that statement has to be true. If you will live in the home, this is the wrong product. See also DSCR loan programs and how a DSCR loan helps investors buy rentals.
Use the DSCR guide and a conversation on your file. I'm not putting a math walkthrough or a calculator in this article.
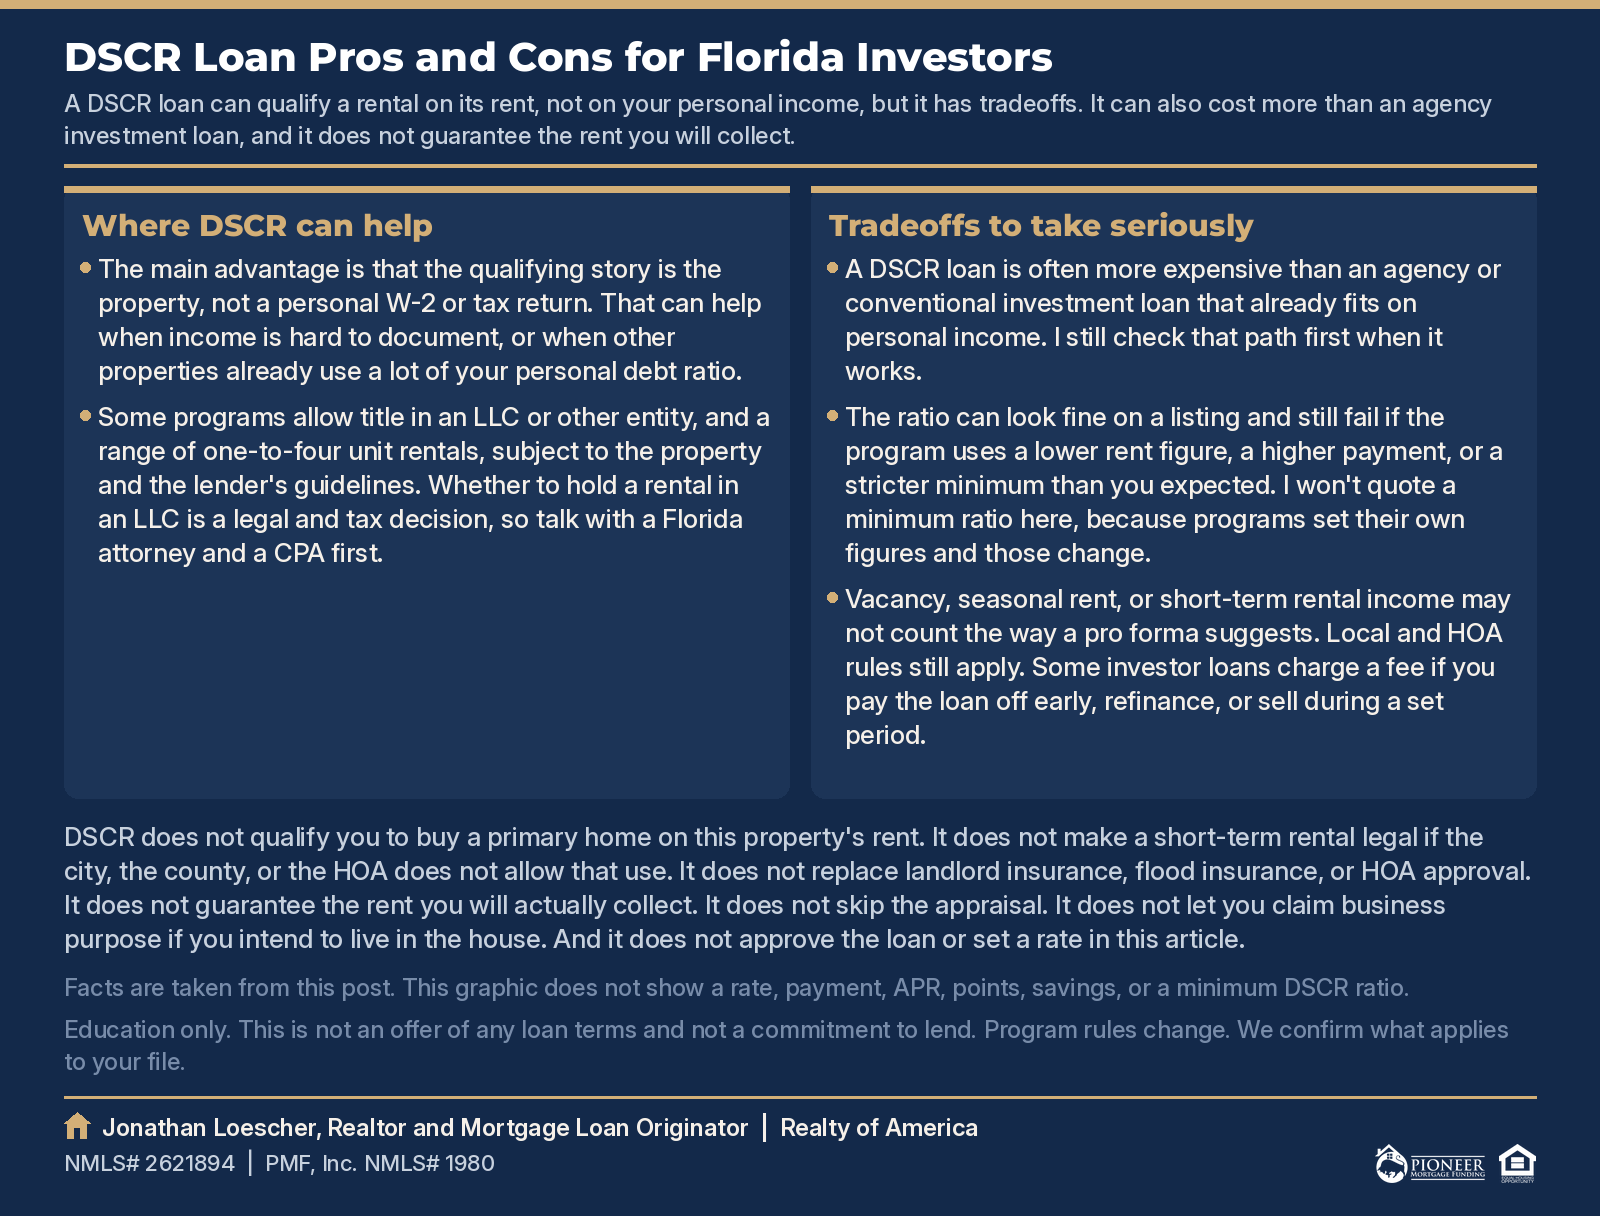
Where DSCR can help
The main advantage is that the qualifying story is the property, not a personal W-2 or tax return. That can help when income is hard to document, or when other properties already use a lot of your personal debt ratio. It can be a cleaner fit than forcing a rental onto a personal bank-statement or tax-return file. Some programs allow title in an LLC or other entity, and a range of one-to-four unit rentals, subject to the property and the lender's guidelines. Whether to hold a rental in an LLC is a legal and tax decision, so talk with a Florida attorney and a CPA first.
It also keeps the underwriting conversation focused on whether the rental can carry its own payment, which is how many investors already think about a purchase. For planning after the loan question is clear, calculating ROI on a Tampa Bay investment property may help. That is not a cash-flow guarantee either.
The tradeoffs to take seriously
A DSCR loan is often more expensive than an agency or conventional investment loan that already fits on personal income. I still check that path first when it works. The ratio can look fine on a listing and still fail if the program uses a lower rent figure, a higher payment, or a stricter minimum than you expected. I won't quote a minimum ratio here, because programs set their own figures and those change.
Vacancy, seasonal rent, or short-term rental income may not count the way a pro forma suggests. Local and HOA rules still apply. See Tampa Bay short-term rental rules. Reserves, credit, property type, and condo or association rules still matter. A strong ratio does not repair a weak building or an occupancy problem.
Prepayment terms are another common tradeoff. Some investor loans charge a fee if you pay the loan off early, refinance, or sell during a set period. Ask whether a prepayment term applies and how it works before you sign. I won't quote a prepayment schedule in this article.
What DSCR does not do
It does not qualify you to buy a primary home on this property's rent. It does not make a short-term rental legal if the city, the county, or the HOA does not allow that use. It does not replace landlord insurance, flood insurance, or HOA approval. It does not guarantee the rent you will actually collect. It does not skip the appraisal or the property-condition review. It does not let you claim business purpose if you intend to live in the house. And it does not approve the loan or set a rate in this article.
When another path may fit better
If your tax returns already support an agency or conventional investment loan, that path may be the simpler fit. If the rent story is weak but your self-employed cash flow is strong, a bank-statement or P&L review may be more accurate than stretching DSCR. Those investor documentation options are in Non-QM for Investors: More Than a DSCR Loan. I don't pick the product first. I look at the property, the occupancy, and the records you actually have.
How I'd weigh the tradeoffs
I start with occupancy and local rental rules, then a realistic payment that includes insurance and dues, then a comparison of DSCR against an agency investment path. If DSCR is the better documentation fit, I'll confirm current terms on your file. Approvals stay conditional.
Apply for a mortgage or book a consultation.
As a Realtor with Realty of America, I can help you find the property. As a Mortgage Loan Originator with PMF, Inc., I can help with the loan. PMF, Inc. is a mortgage broker that works with many wholesale lenders, so I can compare options for your situation. Rates and terms vary by lender, program and borrower, and I can't promise any particular rate or approval. You can use one or both. You don't have to use both.
Common questions
Is DSCR always better than a conventional investment loan?
No. If a conventional or agency investment loan already fits, it can be the simpler path. DSCR is useful when the rent should be the qualifying story, or when a personal-income path is a poor fit.
Does a stronger rent ratio guarantee approval?
No. The ratio is only one part of the file. Property, reserves, credit, occupancy, and program guidelines still matter, and the loan is not approved until underwriting is finished.
Can I use short-term rental income?
Sometimes, and sometimes not. Programs differ, and local or HOA rules still apply. I'll tell you whether the income you have is even usable.
This article is for education only. It is not an offer of any loan terms and not a commitment to lend. Program rules change. We confirm what applies to your file.
Jonathan Loescher, Realtor, Florida real estate license SL3546365, Realty of America. Jonathan Loescher, Mortgage Loan Originator, NMLS 2621894. Mortgage loans are originated through PMF, Inc., NMLS 1980, a Florida licensed Mortgage Broker. Real estate and mortgage services are provided by separate companies, and you don't have to use both. Verify licensing at www.nmlsconsumeraccess.org. Equal Housing Opportunity.
Education only. This is not a commitment to lend. All loans are subject to credit approval, underwriting, and property eligibility. Not all applicants will qualify. Any loan approval is conditional until all underwriting conditions are met. Programs, rates, terms and conditions may change without notice.
Common questions
- How does a DSCR loan help investors buy rentals in Tampa Bay?
- It qualifies a rental on its rent compared to the full payment, not your personal income. It's for business-purpose rentals only. Expect larger down payments and reserves. Check local rental rules first. Any loan approval is conditional until all underwriting conditions are met.
- What's the difference between a second home loan and an investment property loan?
- It depends on how you'll use the home. A second home is for your own use part of the year, and programs limit renting it. An investment property is bought to rent. Investment loans usually need a larger down payment and reserves and price higher. You certify occupancy at closing. Any loan approval is conditional until all underwriting conditions are met.
- How does a bank statement loan work for self-employed buyers in Tampa Bay?
- It uses deposits on your bank statements over many months, not tax returns, to figure income. It's a non-QM option for self-employed buyers whose returns understate cash flow. Expect larger down payments, reserves, and pricing that differs from conventional. Any loan approval is conditional until all underwriting conditions are met.
- Do I need a state license for a short-term rental in Florida?
- Yes, if you rent more than three times a year for stays under 30 days, or advertise it that way. You need a DBPR vacation rental license, either Condo or Dwelling, before you operate. Running without one is a second-degree misdemeanor. You'll also need tax registrations and any local permit your city or county requires.
- Can I do short-term rentals in Tampa?
- It depends on the zoning. A 2022 Tampa court decision upheld a violation for a two-night rental in a South Tampa RS-60 zone, reading the code to require weekly or longer stays there. Other zones may differ, and the code can change. Before you buy, check the parcel's zoning with the city, read any HOA or condo rules, and plan for the state license and taxes.
More Tampa Bay home and loan answers on Ask Jonathan.
Enjoying this? Make us a preferred source on Google.